

TL;DR
Tax audit is mandatory for certain businesses and professionals under Section 44AB of the Income Tax Act, 1961. For FY 2025–26, businesses generally need a tax audit when turnover exceeds ₹1 crore, with the threshold increasing to ₹10 crore where both cash receipts and cash payments do not exceed 5% of the respective totals. For professionals, the general threshold is ₹50 lakh. Certain taxpayers opting out of presumptive taxation may also become liable for audit. For FY 2025–26, the tax audit report is generally due by 30 September 2026. From Tax Year 2026–27, the corresponding provision is Section 63 under the Income Tax Act, 2025.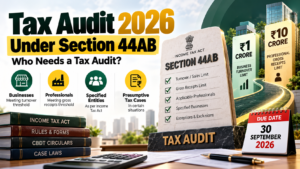
Introduction
A tax audit is an important income tax compliance requirement for businesses and professionals whose accounts fall within the specified conditions under the Income Tax Act. The purpose of a tax audit is to ensure that financial records, income, expenses, deductions and other tax-related information are properly maintained and accurately reported.
For FY 2025–26, tax audit requirements continue to be governed by Section 44AB of the Income Tax Act, 1961. This means businesses and professionals need to check their turnover, gross receipts, cash transactions and presumptive taxation status to determine whether a tax audit is applicable.
The introduction of the Income Tax Act, 2025 also brings a change in section numbering. From Tax Year 2026–27, the corresponding tax-audit provision is Section 63, while the underlying thresholds remain broadly the same.
Understanding these rules is important because missing a mandatory tax audit can result in additional compliance issues and potential penalties.
What Is a Tax Audit Under Section 44AB?
A tax audit is an examination of a taxpayer’s books of accounts by a Chartered Accountant to determine whether the financial information and prescribed particulars are properly maintained and reported.
Section 44AB specifies the circumstances in which a person carrying on business or profession must get their accounts audited.
The tax audit report contains important information relating to turnover, expenses, deductions, depreciation, tax payments, specified transactions and other financial particulars required under the applicable rules.
For FY 2025–26, taxpayers subject to Section 44AB generally use Form 3CA/3CD or Form 3CB/3CD, depending on whether their accounts are already required to be audited under another law.
Who Is Required to Get a Tax Audit in 2026?
The requirement primarily applies to businesses and professionals crossing the prescribed turnover or gross-receipt thresholds. Certain taxpayers using or opting out of presumptive taxation can also fall under the tax-audit provisions.
1. Businesses With Turnover Above ₹1 Crore
A person carrying on business is generally required to get a tax audit if their total sales, turnover or gross receipts exceed ₹1 crore during the relevant previous year.
For example, if a business has annual turnover of ₹1.25 crore, it generally falls within the tax-audit requirement.
However, there is an important higher threshold for businesses with limited cash transactions.
2. Businesses With Turnover Up to ₹10 Crore and Limited Cash Transactions
The tax-audit threshold can increase from ₹1 crore to ₹10 crore if both of the following conditions are satisfied:
- Cash receipts do not exceed 5% of total receipts
- Cash payments do not exceed 5% of total payments
Therefore, a business with turnover of ₹6 crore may not necessarily require a tax audit solely because its turnover exceeds ₹1 crore, provided the applicable cash-transaction conditions are satisfied.
However, if either the cash-receipt or cash-payment condition exceeds the prescribed 5% limit, the enhanced ₹10 crore threshold cannot be relied upon.
3. Professionals With Gross Receipts Above ₹50 Lakh
Professionals are subject to a separate threshold.
If the gross receipts from a profession exceed ₹50 lakh during the relevant previous year, a tax audit is generally required.
This can apply to professionals such as:
- Chartered Accountants
- Lawyers
- Doctors
- Architects
- Engineers
- Consultants
- Interior designers
- Technical professionals
- Other specified professionals
The applicable threshold should be evaluated based on the nature of professional activity and the provisions applicable to that taxpayer.
4. Taxpayers Opting Out of Presumptive Taxation
Tax audit requirements can also arise when a taxpayer who was eligible for presumptive taxation does not follow the presumptive scheme and declares income below the prescribed level, subject to the conditions of the relevant presumptive-tax provisions.
This is particularly important for businesses and professionals using provisions such as presumptive taxation under Sections 44AD and 44ADA of the old Act.
The Income Tax Department specifically includes persons opting out of presumptive taxation and declaring income below the prescribed threshold among cases where tax audit requirements can apply.
Tax Audit Threshold for Business vs Profession
The basic thresholds can be summarized as follows:
| Category | General Tax Audit Threshold |
|---|---|
| Business | Turnover/gross receipts exceeding ₹1 crore |
| Business with prescribed low cash transactions | Up to ₹10 crore threshold |
| Profession | Gross receipts exceeding ₹50 lakh |
| Certain presumptive-tax cases | Depends on applicable presumptive-tax conditions |
The ₹10 crore threshold for businesses is conditional. It is available where both cash receipts and cash payments remain within the prescribed 5% limits.
What Happens If Cash Transactions Exceed 5%?
The cash transaction condition is important for businesses that want to use the enhanced ₹10 crore threshold.
Suppose a business has turnover of ₹5 crore but its cash receipts exceed 5% of total receipts. In that situation, the business cannot automatically rely on the ₹10 crore threshold.
Similarly, if cash payments exceed 5% of total payments, the enhanced threshold condition is not satisfied.
Therefore, businesses should monitor both:
Cash Receipts ÷ Total Receipts
and
Cash Payments ÷ Total Payments
throughout the financial year rather than checking the numbers only at year-end.
Does GST Turnover Automatically Decide Tax Audit Applicability?
Not always.
GST turnover and income-tax turnover are related in many business situations, but tax-audit applicability has to be determined according to the provisions of the Income Tax Act and the nature of receipts.
Businesses should therefore reconcile their books, GST records, sales records, credit notes, advances and other relevant transactions before deciding whether a tax audit is required.
A business should not simply assume that the turnover shown in one compliance system will automatically determine its tax-audit liability.
Tax Audit Due Date for FY 2025–26
For FY 2025–26 / AY 2026–27, the tax audit report is generally due by 30 September 2026 in cases where the regular return due date is 31 October 2026.
The Income Tax Department has clarified that FY 2025–26 tax audits continue under the Income Tax Act, 1961 even though the report may be filed after 1 April 2026.
Transfer-pricing cases can have different timelines because their income-tax return due date is different.
Which Forms Are Used for Tax Audit in 2026?
For FY 2025–26 / AY 2026–27, the existing forms under the Income Tax Act, 1961 continue to apply.
Form 3CA and Form 3CD
Form 3CA-3CD applies where the taxpayer is already required to get accounts audited under another law.
For example, certain companies may already have a statutory audit requirement under company law. In such cases, Form 3CA along with Form 3CD is used for the tax audit reporting requirements.
Form 3CB and Form 3CD
Form 3CB-3CD generally applies where the taxpayer is required to undergo tax audit under Section 44AB but is not required to get the accounts audited under another law.
What Changes Under the Income Tax Act, 2025?
The new Income Tax Act, 2025 introduces a new numbering system for tax provisions.
The old Section 44AB corresponds to Section 63 under the Income Tax Act, 2025.
Importantly, the Income Tax Department has clarified that the basic tax-audit thresholds remain the same:
- Business: ₹1 crore
- Enhanced business threshold: ₹10 crore subject to the 5% cash conditions
- Profession: ₹50 lakh
- Certain presumptive-taxation cases: audit may apply depending on the conditions
For Tax Year 2026–27, the tax-audit report will use the new Form 26, which consolidates the earlier Forms 3CA, 3CB and 3CD.
Tax Audit Under Section 44AB: Example
Consider a business with the following figures:
- Annual turnover: ₹4 crore
- Cash receipts: 2% of total receipts
- Cash payments: 3% of total payments
Since both cash receipts and cash payments remain within the 5% limit, the enhanced ₹10 crore threshold may be available.
Therefore, turnover of ₹4 crore alone would not necessarily make the business liable for tax audit.
Now consider another business:
- Annual turnover: ₹4 crore
- Cash receipts: 7% of total receipts
Since cash receipts exceed 5%, the business cannot rely on the enhanced ₹10 crore threshold and needs to evaluate tax-audit applicability under the normal ₹1 crore threshold.
Common Mistakes Businesses Make About Tax Audit
Assuming ₹1 Crore Always Means Mandatory Audit
The ₹1 crore threshold is not the complete story. Businesses satisfying the prescribed cash-transaction conditions can have an enhanced threshold of ₹10 crore.
Looking Only at Cash Receipts
Both cash receipts and cash payments are relevant when evaluating the enhanced threshold.
Ignoring Presumptive Taxation Rules
A taxpayer opting out of presumptive taxation can become subject to audit depending on the applicable conditions.
Waiting Until the Last Date
Tax audit involves collecting books, invoices, bank statements, expense records, GST data and other supporting information. Waiting until September can make the process unnecessarily difficult.
Confusing FY 2025–26 With Tax Year 2026–27
The transition to the Income Tax Act, 2025 makes tax-year identification particularly important.
FY 2025–26 / AY 2026–27 continues under the old Income Tax Act, 1961 for tax-audit reporting. Tax Year 2026–27 is governed by the Income Tax Act, 2025 and its corresponding Section 63 framework.
Documents Generally Needed for Tax Audit
A taxpayer subject to tax audit should keep financial and compliance records properly organized, including:
- Books of accounts
- Sales and purchase records
- Bank statements
- Cash book
- General ledger
- GST returns and reconciliation
- Invoices and bills
- Expense supporting documents
- Fixed asset records
- Loan and interest details
- TDS records
- Details of related-party transactions
- Details of loans and advances
- Stock records, where applicable
- Previous-year tax-audit reports
- Details of depreciation
- Details of statutory payments
- Other information required for Form 3CD reporting
The exact information required depends on the nature and structure of the taxpayer’s business or profession.
Why Tax Audit Compliance Matters
Tax audit is not simply a formality. It provides a structured review of financial records and helps identify discrepancies before the income-tax return is filed.
Proper tax-audit preparation can help businesses:
- Identify accounting errors
- Reconcile GST and books
- Review expense claims
- Check TDS compliance
- Verify depreciation
- Identify reporting inconsistencies
- Prepare accurate tax returns
- Maintain better financial records
- Reduce the risk of avoidable compliance issues
Conclusion
Tax audit applicability in 2026 depends on more than simply looking at annual turnover. Businesses need to consider the ₹1 crore general threshold, the enhanced ₹10 crore threshold where the prescribed 5% cash conditions are satisfied, and the specific rules applicable to presumptive taxation. Professionals generally need to consider the ₹50 lakh gross-receipts threshold.
For FY 2025–26, Section 44AB of the Income Tax Act, 1961 continues to apply, with the general tax-audit report due by 30 September 2026 in standard cases. From Tax Year 2026–27, the corresponding provision becomes Section 63 under the Income Tax Act, 2025, while the basic thresholds remain unchanged.
Businesses and professionals should evaluate their tax-audit position well before the deadline and maintain their accounting, GST, banking and tax records systematically.
Frequently Asked Questions
1. Who needs a tax audit under Section 44AB in 2026?
Businesses with turnover exceeding ₹1 crore generally require tax audit, subject to the enhanced ₹10 crore threshold where the prescribed cash conditions are satisfied. Professionals generally require audit when gross receipts exceed ₹50 lakh. Certain presumptive-taxation cases can also trigger audit requirements.
2. Is tax audit mandatory above ₹1 crore turnover?
Not necessarily. A business can have an enhanced threshold of ₹10 crore if cash receipts do not exceed 5% of total receipts and cash payments do not exceed 5% of total payments.
3. What is the tax audit limit for professionals in 2026?
The general gross-receipts threshold for professionals is ₹50 lakh.
4. What is the tax audit due date for FY 2025–26?
The general tax-audit report due date for FY 2025–26 / AY 2026–27 is 30 September 2026.
5. Is Section 44AB still applicable in 2026?
Yes, for FY 2025–26 / AY 2026–27, Section 44AB of the Income Tax Act, 1961 continues to govern tax-audit requirements.
6. What is Section 63 under the Income Tax Act, 2025?
Section 63 of the Income Tax Act, 2025 is the corresponding provision for the audit of accounts and broadly replaces the old Section 44AB framework for Tax Year 2026–27 onward.
7. Which forms are used for tax audit for FY 2025–26?
Form 3CA with Form 3CD or Form 3CB with Form 3CD is used depending on whether the taxpayer’s accounts are required to be audited under another law.
8. What form will be used for tax audit under the new Income Tax Act?
For Tax Year 2026–27, Form 26 is prescribed as the new tax-audit report and consolidates the earlier Forms 3CA, 3CB and 3CD.
9. Does exceeding ₹10 crore automatically mean tax audit?
The enhanced threshold is available only where both prescribed cash conditions are satisfied. If the conditions are not satisfied, the normal threshold of ₹1 crore needs to be considered.
10. Can a Chartered Accountant help determine whether tax audit is applicable?
Yes. A Chartered Accountant can review turnover, gross receipts, cash transactions, presumptive-taxation status, books of accounts and other relevant information to determine whether the taxpayer falls within the applicable tax-audit provisions.
Written by CA Junaid Ahmed Khan, Junaid Khan & Co., Bhopal.
