

TL;DR
GST reconciliation before a tax audit helps businesses identify differences between accounting records, outward-supply data reported in GSTR-1 and tax liability declared in GSTR-3B. Common differences arise due to credit notes, amendments, advances, exempt supplies, timing differences, wrong GST rates, missed invoices and accounting adjustments. A proper reconciliation should compare the books with GST returns, classify every difference, verify tax liability and document the reasons before finalizing the tax audit and income-tax return.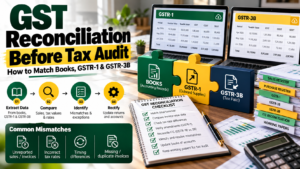
Introduction
GST data has become an important part of a business’s overall tax-compliance framework. Before completing a tax audit, businesses should ensure that their accounting records and GST returns present a consistent picture of sales, purchases, expenses and tax liabilities.
One of the most important checks is the reconciliation between Books of Accounts, GSTR-1 and GSTR-3B.
The three records serve different purposes. Books contain the business’s accounting records, GSTR-1 primarily reports outward supplies, while GSTR-3B is a summary return through which taxpayers declare GST liabilities and eligible input tax credit.
Because these records are prepared for different purposes, a difference does not automatically mean that there is an error. However, every material difference should be identified, investigated and properly explained.
A detailed GST reconciliation before tax audit can help businesses detect under-reporting, excess reporting, incorrect tax rates, missed invoices, duplicate entries and other issues before the financial statements and tax computation are finalized.
Why GST Reconciliation Is Important Before Tax Audit
GST reconciliation is important because turnover reported in GST returns can be compared with the turnover recorded in the financial statements and considered during income-tax compliance.
An unexplained difference can create questions about:
- Turnover
- GST liability
- Sales invoices
- Credit notes
- Taxable and exempt supplies
- Revenue recognition
- Input tax credit
- Tax payments
- Year-end accounting adjustments
A proper reconciliation does not necessarily mean that all three figures must be identical. Instead, the objective is to understand and document legitimate differences.
For example, a business may have income in its books that is outside the scope of GST, or an accounting entry may relate to a transaction reported in a different GST period.
Books vs GSTR-1 vs GSTR-3B: What Is the Difference?
Before beginning reconciliation, it is important to understand what each record represents.
Books of Accounts
The books record the business’s financial transactions, including:
- Sales
- Purchases
- Expenses
- Receipts
- Credit notes
- Debit notes
- Other income
- GST collected
- GST paid
- Receivables and payables
The financial statements are ultimately prepared from these accounting records.
GSTR-1
GSTR-1 contains details of outward supplies reported by the taxpayer.
Depending on the taxpayer and transaction, it can include information relating to:
- Business-to-business supplies
- Business-to-consumer supplies
- Export supplies
- Credit notes
- Debit notes
- Amendments
- Advances in applicable cases
- Other outward-supply information
GSTR-3B
GSTR-3B is a summary return used to declare GST liability and eligible input tax credit and to discharge the resulting tax liability.
Therefore, GSTR-3B should not be expected to contain the same invoice-level information as GSTR-1.
The reconciliation should focus on whether the underlying transactions and tax liabilities have been correctly captured across the three records.
Step 1: Extract the Sales Data From the Books
The first step is to obtain the complete sales data from the accounting system for the relevant financial year.
The reconciliation file should ideally include:
- Invoice number
- Invoice date
- Customer GSTIN
- Taxable value
- CGST
- SGST/UTGST
- IGST
- GST rate
- Place of supply
- Credit notes
- Debit notes
- Amendments
- Exempt supplies
- Zero-rated supplies
- Non-GST supplies
The sales register should be finalized before comparing it with GST returns.
Step 2: Download and Compile GSTR-1 Data
Businesses should compile their GSTR-1 data for all relevant tax periods.
Rather than checking only the annual total, an invoice-level or transaction-level comparison is more useful.
The reconciliation should consider:
- B2B invoices
- B2C supplies
- Export invoices
- Credit notes
- Debit notes
- Amendments
- Advances where applicable
- Nil-rated/exempt supplies
- Other outward supplies
Businesses should also check whether invoices reported in one period were amended or cancelled in a subsequent period.
Step 3: Reconcile GSTR-1 With GSTR-3B
The next step is to compare outward-supply information reported in GSTR-1 with the corresponding liability declared in GSTR-3B.
The comparison should cover:
- Taxable turnover
- IGST liability
- CGST liability
- SGST/UTGST liability
- Reverse-charge liability where relevant
- Credit notes
- Adjustments
- Amendments
A mismatch may be caused by timing differences, corrections or other legitimate adjustments.
However, unexplained differences should be investigated before tax-audit reporting is finalized.
Step 4: Compare GST Turnover With Books
After reconciling GSTR-1 and GSTR-3B, compare GST turnover with the sales and revenue figures in the books.
A simple reconciliation can be structured as:
Turnover as per Books
Add: Items recorded in books but not reported in GST returns, where applicable
Less: Items reported in GST returns but not recognized as revenue in the books, where applicable
Add/Less: Timing differences, credit notes, advances and other reconciling items
Equals: GST-reconciled turnover
The exact format should depend on the nature of the business and the transactions involved.
Common Reasons for Differences Between Books and GSTR-1
1. Credit Notes
A credit note may be recorded in the books in one period but reported in a different GST period.
This can create a temporary mismatch.
2. Debit Notes
Debit notes can similarly create differences when accounting recognition and GST reporting occur in different periods.
3. Amendments
An invoice may initially be reported incorrectly and subsequently amended through the GST return.
If the books reflect the corrected transaction while the return history contains both original and amended reporting, a simple total comparison may be misleading.
4. Exempt or Non-GST Income
Not every amount appearing in the income statement is necessarily taxable under GST.
Examples can include certain:
- Interest income
- Exempt supplies
- Non-GST supplies
- Other income items
The nature of each item should be reviewed rather than assuming that all accounting revenue must appear as taxable turnover in GSTR-1.
5. Timing Differences
An invoice may be accounted for at one point while its GST reporting falls into another tax period depending on the applicable GST rules and transaction circumstances.
Year-end transactions require particular attention.
Common Reasons for Differences Between GSTR-1 and GSTR-3B
Wrong Tax Amount
An invoice may be correctly reported in GSTR-1 but the corresponding tax liability may not have been correctly reflected in GSTR-3B.
Missed Liability
A taxable supply may appear in GSTR-1 but be missing or incorrectly reported in the summary liability of GSTR-3B.
Credit Note Adjustment
Credit notes can affect the comparison between outward-supply details and summary tax liability.
Amendments
Changes made through amendments can cause period-wise differences.
Timing Differences
A transaction may be reflected differently across reporting periods.
Every such difference should be traced to the underlying invoice or adjustment.
How to Reconcile GST Turnover Before Tax Audit
A practical reconciliation process can follow these stages:
Stage 1: Books to GSTR-1
Compare the sales register with outward-supply details reported in GSTR-1.
Identify:
- Missing invoices
- Duplicate invoices
- Wrong GSTIN
- Incorrect taxable value
- Incorrect tax rate
- Credit notes
- Debit notes
- Amendments
Stage 2: GSTR-1 to GSTR-3B
Compare the outward liability reported in GSTR-1 with the liability declared in GSTR-3B.
Identify differences in:
- Taxable value
- IGST
- CGST
- SGST/UTGST
- Other applicable liability categories
Stage 3: Books to GSTR-3B
Compare the books with the summary liability actually declared in GSTR-3B.
This helps identify cases where accounting records indicate a GST liability that was not properly reflected in the return.
Stage 4: Investigate Every Material Difference
Do not simply add an adjustment called “reconciliation difference.”
Each material difference should have an explanation and supporting evidence.
GST Reconciliation Example
Suppose a business records annual sales of ₹5 crore in its books.
Its GSTR-1 data shows taxable and other outward supplies totaling ₹4.85 crore.
At first glance, there is a ₹15 lakh difference.
However, further investigation shows:
- ₹5 lakh relates to exempt income
- ₹4 lakh relates to a non-GST item
- ₹3 lakh relates to a year-end accounting adjustment
- ₹3 lakh relates to a credit note reported in the subsequent period
The difference is therefore not necessarily an undisclosed GST liability.
This example shows why businesses should explain the difference instead of simply comparing two headline numbers.
How to Reconcile GST Tax Liability
Turnover reconciliation alone is not enough.
Businesses should separately reconcile GST tax liability.
A liability reconciliation can include:
| Particular | Books | GSTR-1 | GSTR-3B | Difference | Reason |
|---|---|---|---|---|---|
| Taxable Turnover | ₹X | ₹X | ₹X | ₹X | Timing/other adjustment |
| IGST | ₹X | ₹X | ₹X | ₹X | Reconciled |
| CGST | ₹X | ₹X | ₹X | ₹X | Reconciled |
| SGST/UTGST | ₹X | ₹X | ₹X | ₹X | Reconciled |
| Credit Notes | ₹X | ₹X | ₹X | ₹X | Period difference |
The actual values should be populated from the business’s accounting and GST records.
Reconcile Credit Notes and Debit Notes Separately
Credit notes and debit notes are frequent sources of reconciliation differences.
Businesses should maintain a separate schedule containing:
- Original invoice number
- Original invoice date
- Credit/debit note number
- Note date
- Taxable value
- GST amount
- Accounting period
- GST reporting period
- Reason for adjustment
This makes it easier to explain differences during the tax-audit process.
Check GST Rate and Classification Errors
A business may have reported the correct invoice amount but applied an incorrect GST rate.
For example, if a product should be taxed at one rate but has been reported using another rate, the turnover may match while the tax liability does not.
Therefore, reconciliation should cover both:
Value reconciliation + Tax reconciliation
Businesses should also review HSN/SAC classification wherever relevant.
Reconcile Year-End Transactions Carefully
March transactions deserve special attention before a tax audit.
Businesses should review:
- March sales
- March credit notes
- March debit notes
- Unbilled revenue
- Advances
- Goods dispatched around year-end
- Invoices reported in April
- Amendments made after year-end
A transaction recorded in March in the books but reported in April in GST returns may create a year-end difference that needs to be documented.
Reconcile Reverse Charge Transactions
Reverse-charge transactions should be reviewed separately because the reporting mechanism differs from ordinary outward supplies.
Businesses should identify applicable reverse-charge transactions and verify:
- Nature of supply
- Taxable value
- GST liability
- Tax payment
- Eligible ITC
- Return reporting
The books, GST returns and supporting documents should tell a consistent story.
GST Reconciliation and Input Tax Credit
Although the primary focus of this reconciliation is books, GSTR-1 and GSTR-3B, businesses should also review the relationship between purchases and ITC.
A useful additional reconciliation is:
Purchase Register → Supplier Data → GSTR-2B → IMS, where applicable → GSTR-3B
The presence of an invoice in GSTR-2B does not by itself establish that ITC is legally available. Eligibility conditions under GST law still need to be examined.
Businesses should identify:
- Missing invoices
- Duplicate ITC
- Supplier filing delays
- Wrong GSTIN
- Credit notes
- Ineligible ITC
- Reversals
- Amendments
This review can prevent incorrect ITC claims from carrying into the tax-audit period.
How GST Reconciliation Helps With Income-Tax Audit
GST reconciliation can provide useful support when finalizing income-tax audit figures.
It helps businesses verify whether:
- Sales turnover is complete
- Revenue has been correctly recorded
- GST liabilities are properly accounted for
- Credit notes are correctly treated
- Taxable and non-taxable income are distinguished
- Year-end adjustments are documented
The objective is not to make every GST and accounting figure identical. The objective is to ensure that every difference is genuine, explainable and supported by records.
Documents to Keep Ready for GST Reconciliation
Businesses should maintain:
- Sales register
- Purchase register
- General ledger
- GST ledgers
- GSTR-1
- GSTR-3B
- GSTR-2B
- IMS records, where applicable
- Tax invoices
- Credit notes
- Debit notes
- E-invoices, where applicable
- E-way bills, where relevant
- GST payment challans
- Bank statements
- Customer/vendor reconciliation
- Year-end adjustment schedules
Maintaining these records systematically can make both GST and income-tax compliance easier.
Common GST Reconciliation Mistakes Before Tax Audit
Comparing Only Annual Totals
Annual totals may hide month-wise errors. Period-wise reconciliation is generally more useful.
Ignoring Credit Notes
Credit notes can materially affect taxable turnover and GST liability.
Treating Every Difference as an Error
Some differences are legitimate accounting or reporting differences. They need explanation rather than automatic correction.
Ignoring Amendments
Original and amended GST data should be reviewed together.
Failing to Reconcile Tax Amounts
A turnover match does not necessarily mean that GST liability is correct.
Not Documenting Reasons
A reconciliation without explanations is difficult to use during an audit or future assessment.
Ignoring March-April Differences
Year-end timing differences are among the most common reconciliation issues.
GST Reconciliation Checklist Before Tax Audit
Before finalizing the tax audit, businesses should check:
- Sales register reconciled with GSTR-1
- GSTR-1 reconciled with GSTR-3B
- Books reconciled with GSTR-3B
- Credit notes verified
- Debit notes verified
- Amendments checked
- GST rates reviewed
- HSN/SAC classification reviewed
- Exempt and non-GST income identified
- Reverse-charge transactions checked
- March transactions reconciled
- GST payments reconciled
- ITC reviewed
- GSTR-2B reconciled where applicable
- IMS records reviewed where applicable
- Material differences documented
- Final GST turnover reconciled with financial statements
Conclusion
GST reconciliation before tax audit is an important financial-control and compliance exercise. Businesses should not wait until the tax-audit deadline to compare their books with GSTR-1 and GSTR-3B.
A proper reconciliation should move beyond simply comparing turnover figures. Businesses should investigate invoice-level differences, credit notes, amendments, GST rates, tax liabilities, reverse-charge transactions, year-end adjustments and ITC-related issues.
The most effective approach is to create a structured reconciliation between Books → GSTR-1 → GSTR-3B, investigate every material difference and maintain supporting documentation for genuine adjustments.
When this process is completed before the tax audit is finalized, businesses can reduce the risk of unexplained GST differences and make the preparation of their income-tax return and audit documentation much smoother.
Frequently Asked Questions
1. Why should GST reconciliation be done before a tax audit?
GST reconciliation helps identify differences between accounting records and GST returns before the tax audit and income-tax return are finalized. It can help detect missing invoices, incorrect tax rates, credit-note differences and other reporting issues.
2. Should books, GSTR-1 and GSTR-3B have exactly the same turnover?
Not necessarily. Legitimate differences can arise from exempt income, non-GST items, timing differences, credit notes, amendments and other transactions. Every material difference should be properly explained.
3. What should be reconciled between GSTR-1 and GSTR-3B?
Businesses should compare taxable turnover and applicable IGST, CGST and SGST/UTGST liabilities, along with credit notes, amendments and other relevant adjustments.
4. What are the common reasons for GST reconciliation differences?
Common reasons include missed invoices, duplicate reporting, credit notes, debit notes, amendments, timing differences, incorrect GST rates, exempt supplies, non-GST income and year-end accounting adjustments.
5. Should GST turnover match income-tax turnover?
Not always. Income-tax books can contain items that are outside GST or can have accounting and GST timing differences. The important point is that genuine differences should be identified and properly documented.
6. How should March sales be reconciled before tax audit?
March sales should be compared with GSTR-1 and GSTR-3B reporting and checked for invoices reported in subsequent periods, credit notes, amendments and other year-end adjustments.
7. Is GSTR-2B part of GST reconciliation?
Yes. Although GSTR-2B is primarily relevant to input tax credit reconciliation rather than outward-supply reconciliation, businesses should review it against purchase records and GSTR-3B when preparing for tax compliance.
8. Does an invoice appearing in GSTR-2B automatically make ITC eligible?
No. GSTR-2B is an important reconciliation source, but the taxpayer must still satisfy the applicable legal conditions for claiming ITC.
9. What documents are needed for GST reconciliation?
Businesses should generally keep sales and purchase registers, GSTR-1, GSTR-3B, GSTR-2B, invoices, credit notes, debit notes, GST ledgers, payment records, e-invoices and other relevant supporting documents.
10. Who can help with GST reconciliation before a tax audit?
A Chartered Accountant or qualified tax professional can review the books, GST returns, reconciliations and tax-audit requirements, identify material differences and help prepare supporting schedules before the audit is finalized.
Written by CA Junaid Ahmed Khan, Junaid Khan & Co., Bhopal.
