

Advance Tax Payment Guide 2026: Due Dates, Calculation & Penalties for Late Payment
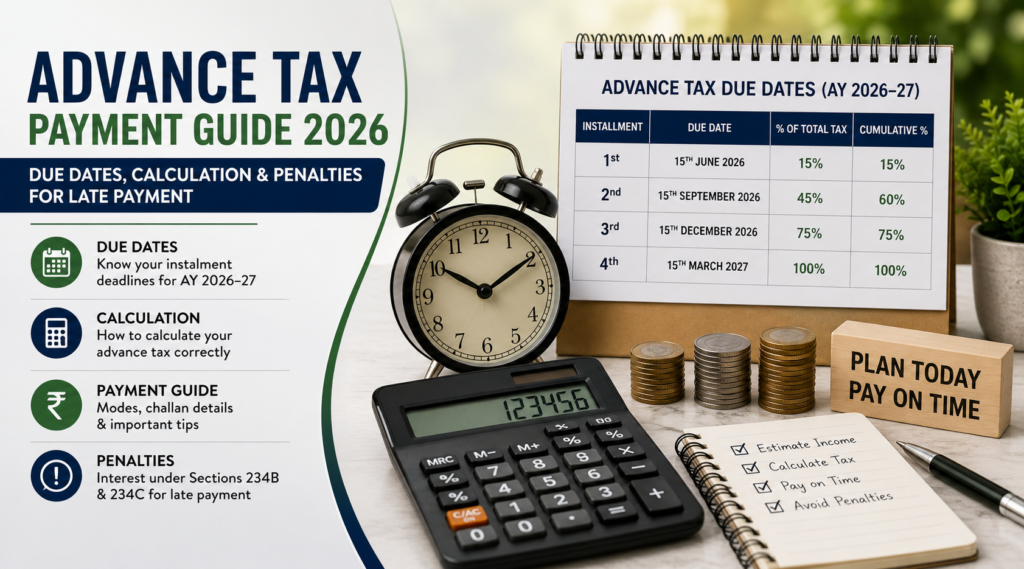
TL;DR Advance tax is a system under which eligible taxpayers pay their estimated income tax during the financial year instead of waiting until the year ends. For FY 2026–27 (AY 2027–28), taxpayers liable to pay advance tax generally make payments in instalments during the financial year. For most taxpayers, the statutory schedule is: Due Date Cumulative Advance Tax Payable 15 June 2026 15% 15 September 2026 45% 15 December 2026 75% 15 March 2027 100% For taxpayers covered by the presumptive taxation provisions under Sections 44AD or 44ADA, the applicable advance tax payment is generally 100% by 15 March. Missing or underpaying advance tax can result in interest under Sections 234B and 234C, subject to the conditions prescribed under the Income Tax Act. What Is Advance Tax? Advance tax is income tax paid during the financial year on income that is expected to be earned during that same year. It is commonly described as a “pay-as-you-earn” tax system. Instead of waiting until the end of the financial year to calculate and pay the entire tax liability, eligible taxpayers estimate their annual tax and pay it in instalments. For example, a freelancer expects to earn substantial professional income throughout FY 2026–27. Rather than waiting until March 2027, the taxpayer estimates the annual taxable income and pays the required tax progressively during the year. This helps both taxpayers and the tax administration manage tax liabilities more systematically. Who Is Required to Pay Advance Tax? Under Section 208, advance tax generally applies when the estimated tax liability for the financial year is ₹10,000 or more, subject to the conditions and exemptions provided by law. Advance tax can therefore apply to taxpayers such as: Business owners Freelancers Consultants Doctors Lawyers Chartered professionals Landlords Traders Investors with taxable income Salaried individuals with substantial additional income Companies and other taxpayers Senior Citizen Exception A resident individual who: is 60 years of age or more, and does not have income from a business or profession, is generally not liable to pay advance tax. This exception should be checked against the taxpayer’s actual circumstances and the applicable provisions. Advance Tax Due Dates for FY 2026–27 For taxpayers following the regular advance-tax schedule, the payment structure is cumulative. Instalment Due Date Minimum Cumulative Payment 1st 15 June 2026 15% 2nd 15 September 2026 45% 3rd 15 December 2026 75% 4th 15 March 2027 100% Example Suppose your estimated advance tax liability for FY 2026–27 is: ₹2,00,000 Your cumulative target would approximately be: By 15 June: ₹30,000 By 15 September: ₹90,000 By 15 December: ₹1,50,000 By 15 March: ₹2,00,000 These percentages are cumulative, not additional amounts payable at each date. So, if you have already paid ₹30,000 in June, you do not pay another ₹90,000 in September. You need to bring your cumulative payment up to ₹90,000. How Is Advance Tax Calculated? Advance tax should not be calculated simply by applying the tax slab to gross income. A proper calculation generally follows this sequence: Step 1: Estimate Total Income Consider expected income from all relevant sources, including: Salary Business income Professional income Rental income Interest Dividends Capital gains Other taxable income Step 2: Estimate Eligible Deductions Depending on the applicable tax regime and taxpayer category, consider eligible deductions. Step 3: Calculate Tax Calculate tax using the applicable provisions and tax regime. Step 4: Consider Rebate Apply any eligible rebate available under the applicable provisions. Step 5: Add Applicable Surcharge and Cess Where applicable, consider: Surcharge Health and Education Cess Other applicable components Step 6: Reduce TDS/TCS This is critical. Advance tax is generally calculated after considering taxes already expected to be deducted or collected and available for credit. Basic Formula Estimated Tax Liability − TDS/TCS Credits = Estimated Advance Tax Liability The resulting amount should then be considered against the applicable ₹10,000 threshold and instalment requirements. Example of Advance Tax Calculation Suppose a freelancer estimates the following income for FY 2026–27: Particular Amount Professional income ₹14,00,000 Interest income ₹50,000 Gross income ₹14,50,000 Eligible adjustments/deductions As applicable Estimated final tax liability ₹1,20,000 Expected TDS ₹30,000 Advance tax to be paid ₹90,000 The taxpayer should then distribute the ₹90,000 estimated advance-tax liability according to the applicable instalment schedule. This is only an illustrative example. The actual liability depends on the taxpayer’s income, tax regime, deductions, special-rate income and applicable provisions. Advance Tax for Salaried Employees Many salaried employees assume advance tax never applies to them. That is not always correct. If your employer deducts sufficient TDS from your salary, you may not need to separately pay advance tax. However, advance tax can become relevant if you earn significant additional income such as: Rental income Interest income Capital gains Freelance income Consultancy income Dividend income Other taxable receipts Example Suppose your employer deducts ₹1,50,000 as TDS. You later earn ₹2,00,000 in taxable capital gains and ₹80,000 in interest income. Your total final tax liability may exceed the tax already covered through TDS. The resulting shortfall may need to be addressed through advance tax to avoid interest exposure, subject to the applicable provisions. Advance Tax for Freelancers and Professionals Advance tax is particularly important for self-employed professionals because income is not necessarily accompanied by regular monthly TDS. Professionals such as: Consultants Doctors Lawyers Designers Architects Software professionals Marketing consultants Independent advisors may have substantial tax liabilities even after considering TDS deducted by clients. A good practice is to estimate income quarter by quarter rather than making a single annual guess. This is particularly useful when professional receipts fluctuate. Advance Tax for Businesses Business owners should integrate advance-tax planning with monthly or quarterly accounting. A business may experience: Seasonal sales Variable margins Large expenses New contracts Inventory changes Asset purchases Sudden revenue increases Therefore, advance tax should ideally be reviewed as financial results become clearer. Recommended Approach Monthly bookkeeping → Profit estimation → Tax projection → TDS/TCS reconciliation → Advance-tax planning This approach reduces the risk of reaching March with an unexpectedly large tax liability. Advance Tax on Capital Gains Capital gains can make
New Tax Regime vs Old Tax Regime FY 2026–27: Which One Can Save You More Tax?
TL;DR The new tax regime is the default tax regime for eligible individual taxpayers, but the old regime continues to be available to eligible taxpayers who choose to opt out. The Income Tax Department specifically advises taxpayers to compare their tax liability under both regimes before making a choice. For FY 2026–27 (AY 2027–28), the new regime generally offers lower rates across more income slabs and permits fewer deductions and exemptions. The old regime has higher slab rates but allows a wider range of deductions and exemptions. The important question is therefore not simply “Which regime has lower tax rates?” It is: Which regime produces the lower final tax liability after considering your income, deductions, exemptions, investments and other eligible tax benefits? Introduction Choosing between the new tax regime and old tax regime can have a significant impact on your annual tax liability. Two taxpayers earning the same salary may end up paying different amounts of tax because their deductions, exemptions, investments, home-loan interest and other eligible benefits may be completely different. For FY 2026–27, the new regime continues to be the default regime for eligible taxpayers. However, taxpayers can opt for the old regime if it is more beneficial for their circumstances. This makes tax planning more important than simply following whichever regime appears popular. What Changed for FY 2026–27? The new regime continues to have a wider range of income slabs and comparatively lower rates. For individuals below 60 years of age, the official Income Tax Department’s AY 2026–27 guidance lists the following new-regime structure: Taxable Income New Regime Rate Up to ₹4 lakh Nil ₹4 lakh–₹8 lakh 5% ₹8 lakh–₹12 lakh 10% ₹12 lakh–₹16 lakh 15% ₹16 lakh–₹20 lakh 20% ₹20 lakh–₹24 lakh 25% Above ₹24 lakh 30% The Department also states that the Section 87A rebate under the new regime was increased to ₹60,000 for total income up to ₹12 lakh, applicable from AY 2026–27. Important: FY 2026–27 corresponds to AY 2027–28. Taxpayers should always verify the provisions applicable to the relevant assessment year before filing. New Tax Regime Slabs for FY 2026–27 For an individual below 60 years of age, the new regime provides: Income Slab Tax Rate Up to ₹4,00,000 0% ₹4,00,001–₹8,00,000 5% ₹8,00,001–₹12,00,000 10% ₹12,00,001–₹16,00,000 15% ₹16,00,001–₹20,00,000 20% ₹20,00,001–₹24,00,000 25% Above ₹24,00,000 30% These are the official slabs published by the Income Tax Department for AY 2026–27. Taxpayers should also consider applicable rebate, surcharge, marginal relief and 4% Health and Education Cess while calculating the final liability. Old Tax Regime Slabs for FY 2026–27 For individuals below 60 years, the traditional regime continues to use the following basic slabs: Income Slab Tax Rate Up to ₹2,50,000 0% ₹2,50,001–₹5,00,000 5% ₹5,00,001–₹10,00,000 20% Above ₹10,00,000 30% The old regime may nevertheless become attractive for taxpayers who have substantial eligible deductions and exemptions. New Tax Regime vs Old Tax Regime: Key Differences Feature New Tax Regime Old Tax Regime Default regime Yes No Tax rates Generally lower Generally higher Number of slabs More Fewer 80C deduction Generally not available Available, subject to conditions 80D deduction Generally restricted/not available Available, subject to conditions HRA exemption Generally not available Available, subject to conditions Standard deduction for salaried taxpayers Available Available Tax planning complexity Lower Higher Suitable for Taxpayers with fewer deductions Taxpayers with substantial eligible deductions The Income Tax Department describes the core distinction clearly: the new regime offers lower rates with fewer deductions and exemptions, while the old regime permits various deductions and exemptions. What Deductions Are Available Under Each Regime? This is where many taxpayers make the wrong decision. The old regime can be beneficial when a taxpayer has significant eligible deductions and exemptions. Common Old-Regime Tax Benefits Depending on eligibility and applicable conditions, these can include: Section 80C investments Section 80D medical insurance Section 80CCD(1B) additional NPS contribution HRA exemption Home-loan interest under applicable provisions Certain education-loan interest deductions Certain disability-related deductions Other deductions permitted under the Income Tax Act The exact availability depends on the taxpayer’s circumstances and the relevant provision. Is Section 80C Available Under the New Tax Regime? Generally, the popular Section 80C deduction is not available under the new regime, except for specific deductions that remain permitted under the applicable provisions. This is an important distinction for taxpayers who regularly claim deductions for: PPF ELSS Life insurance premiums Eligible tuition fees Certain principal repayments Other qualifying Section 80C investments/payments A taxpayer who has historically relied heavily on 80C should therefore calculate the tax under both regimes before deciding. Standard Deduction Under the Two Regimes For salaried taxpayers, standard deduction remains an important component of the comparison. The new regime provides a higher standard deduction for eligible salaried/pension income compared with the old regime under the current rules. This means taxpayers should compare taxable income after the applicable standard deduction, rather than comparing gross salary directly with the tax slabs. For example: Gross Salary → Applicable Standard Deduction → Taxable Salary → Other eligible adjustments → Tax Calculation This distinction becomes particularly important when comparing salaries around ₹10 lakh, ₹12 lakh, ₹15 lakh and ₹20 lakh. Section 87A Rebate Under the New Regime The Section 87A rebate is one of the most important features of the current new regime. For AY 2026–27, the Income Tax Department states that the rebate was increased from ₹25,000 to ₹60,000 for eligible resident individuals with total income up to ₹12 lakh. This significantly changes the tax calculation for taxpayers around the ₹12 lakh income level. However, taxpayers should not interpret this as meaning that every person earning exactly ₹12 lakh or less automatically has zero tax in every situation. Eligibility conditions and the nature of income must be considered. Which Tax Regime Is Better? There is no single answer that works for every taxpayer. The Income Tax Department itself states that the better option varies from person to person and recommends comparing the tax liability under both regimes before selecting one. The New Regime May Be More Attractive If: You have relatively few deductions. You
Income Tax Notice in 2026: Common Reasons, Types & How to Respond Online
TL;DR Receiving an Income Tax Notice does not automatically mean that you have committed tax evasion or owe a penalty. A communication may be issued because the Income Tax Department requires clarification, detects a mismatch, processes an adjustment, finds the return defective, initiates scrutiny, or identifies a potential tax demand. The most important steps are to verify the communication, understand the applicable section, check the response deadline, reconcile the information with your ITR, AIS and Form 26AS, gather supporting documents, and submit an accurate response through the appropriate facility on the Income Tax e-Filing portal. The Income Tax Department’s e-Proceedings facility allows registered taxpayers or their authorized representatives to view and respond electronically to notices, intimations and letters. What Is an Income Tax Notice? An Income Tax notice is an official communication issued by the Income Tax Department concerning a taxpayer’s return, reported income, deductions, taxes, financial transactions, assessment or another compliance matter. Not every communication means additional tax is payable. Depending on its nature, the Department may simply be: Processing your return. Requesting additional information. Asking you to correct a defective return. Proposing an adjustment. Seeking clarification about a transaction. Conducting scrutiny. Communicating an outstanding demand. Therefore, the first step should never be panic or immediate payment. It should be understanding exactly what the communication says and what action it requires. Why Did You Receive an Income Tax Notice? Modern tax administration increasingly relies on information reported by employers, banks, financial institutions, GST systems and other reporting entities. This makes accurate reconciliation before ITR filing extremely important. Here are some common situations that can lead to a notice or further verification. 1. AIS or Form 26AS Does Not Match Your ITR A mismatch between information available with the Department and the information reported in your Income Tax Return can attract attention. For example, AIS or Form 26AS may contain: Salary information. Interest income. Dividend income. Securities transactions. TDS/TCS information. Other reportable financial transactions. If your ITR does not correctly account for relevant income or tax information, clarification or correction may be required. Mismatches between ITR data and AIS/Form 26AS are among the commonly cited reasons for tax communications. Practical Tip Always reconcile your Form 16, Form 16A, AIS, TIS and Form 26AS with your own financial records before submitting your return. 2. Income From One or More Sources Was Not Reported A taxpayer may correctly report salary or business income but accidentally forget another income source. Examples can include: Savings or fixed-deposit interest. Rental income. Capital gains. Dividend income. Freelance income. Professional receipts. Income from investments. The possibility of mismatches increases when taxpayers rely entirely on one document rather than reviewing their complete financial information. 3. Incorrect or Unsubstantiated Deduction Claims Deductions and exemptions should be claimed only when the taxpayer meets the applicable legal conditions and can maintain appropriate supporting documentation. Unusual or incorrect claims may require clarification. Maintain records supporting significant claims rather than trying to reconstruct them only after receiving a notice. 4. High-Value Transactions Require Reconciliation Certain transactions reported through the financial system may need to be properly reflected in your tax position. Examples can include: Purchase or sale of property. Large investments. Significant securities transactions. High-value deposits or receipts. A high-value transaction does not by itself establish wrongdoing. The key issue is whether the transaction and its tax implications have been correctly reported where required. 5. GST Turnover and Income Tax Records Do Not Match For business taxpayers, consistency between financial statements, GST records and Income Tax reporting is important. For example, a substantial difference between turnover reflected through GST-related records and the figures reported for Income Tax purposes may require reconciliation or explanation. GST/ITR turnover differences are also among the circumstances commonly discussed in relation to scrutiny. 6. Your Return Contains Errors or Is Incomplete Incorrect or incomplete information can result in a defective return communication. Possible issues include: Missing mandatory information. Incomplete schedules. Incorrect tax details. Income information not properly reported. Other inconsistencies affecting the validity of the return. A defective return notice should be addressed within the deadline specified in the communication. 7. TDS Information Does Not Match TDS-related mismatches can arise because of: Incorrect PAN. Incorrect TDS amount. Deductor reporting errors. Incorrect challan information. Delayed TDS deposit or reporting. Such mismatches can affect return processing and tax credit claims. Common Types of Income Tax Notices You Should Understand Different communications serve different purposes. Identifying the applicable provision is therefore essential before preparing your response. Section 139(9) – Defective Return A communication under Section 139(9) may be issued when the return is considered defective because required information is missing or contains specified deficiencies. What Should You Do? Review the defect mentioned in the notice, compare it with the filed ITR, correct the relevant information, and submit the response within the prescribed time. Section 143(1) – Intimation After Processing An intimation under Section 143(1) is associated with processing of the Income Tax Return. Processing may result in: No additional amount payable. Refund determination. Adjustment or tax demand. Taxpayers should compare the figures in the intimation with the original return before taking further action. Section 143(2) – Scrutiny Notice A scrutiny notice requires considerably more attention. Scrutiny can involve examination of matters such as reported income, deductions, losses, financial transactions or other information relevant to the assessment. Illustrative situations associated with scrutiny can include significant AIS/Form 26AS mismatches, undisclosed high-value transactions and differences between GST-related turnover and tax records. What Should You Do? Do not send a rushed explanation. Review the issue carefully and organize documentary evidence supporting the figures reported in the return. Section 142(1) – Inquiry Before Assessment A notice under Section 142(1) may seek information, accounts or documents required for assessment-related purposes. Depending on the circumstances, taxpayers may be asked to provide financial information or explanations concerning specific transactions. Section 148 – Income Escaping Assessment A notice relating to reassessment requires careful professional review because it can involve income that the Department believes may not have been appropriately assessed
Top 20 Income Tax Deductions You Should Not Miss While Filing ITR in 2026
TL;DR Claiming eligible income tax deductions can significantly reduce your taxable income and improve your overall tax efficiency. Whether you’re a salaried employee, freelancer, professional, or business owner, understanding available deductions under the Income-tax Act helps you file an accurate Income Tax Return (ITR) while making the most of legitimate tax-saving opportunities. Proper documentation and timely tax planning are key to maximizing these benefits. Introduction Many taxpayers focus only on filing their Income Tax Return before the deadline but overlook one of the most important aspects of tax planning—claiming eligible deductions. Missing even a few legitimate deductions may result in paying more tax than required. India’s Income-tax Act provides several deductions that encourage savings, investments, insurance coverage, retirement planning, education, healthcare, and charitable giving. Understanding these provisions allows taxpayers to reduce their taxable income while remaining fully compliant with tax laws. This guide explains twenty of the most commonly claimed deductions that taxpayers should review before filing their ITR in 2026. Why Income Tax Deductions Matter Income tax deductions reduce the amount of income on which tax is calculated. By lowering taxable income, they can help individuals reduce their overall tax liability while encouraging long-term financial planning. Effective tax planning can help you: Reduce taxable income. Improve long-term savings. Build retirement wealth. Protect your family through insurance. Support higher education. Manage healthcare expenses. Encourage disciplined investments. Avoid last-minute tax planning. Top 20 Income Tax Deductions 1. Section 80C One of the most widely used tax-saving provisions, Section 80C covers eligible investments and specified expenditures up to the applicable statutory limit under the Income-tax Act. Common eligible investments include: Public Provident Fund (PPF) Employees’ Provident Fund (EPF) Equity Linked Savings Scheme (ELSS) National Savings Certificate (NSC) Tax-saving Fixed Deposits Sukanya Samriddhi Yojana Life Insurance Premiums Principal repayment of eligible home loans Children’s tuition fees (subject to conditions) 2. Section 80CCD(1B) This deduction is available for eligible contributions to the National Pension System (NPS), over and above certain other eligible deductions, subject to applicable limits. 3. Section 80D Taxpayers may claim deductions for eligible health insurance premiums paid for themselves and specified family members, subject to the limits prescribed under the Income-tax Act. 4. Section 80DD This provision provides deductions for eligible expenditure incurred towards the maintenance and care of specified dependents with disabilities, subject to prescribed conditions. 5. Section 80DDB Eligible taxpayers may claim deductions for specified medical treatment expenses for certain notified diseases, subject to documentation and applicable conditions. 6. Section 80E Individuals may claim deductions for eligible interest paid on education loans taken for higher education, as per applicable provisions. 7. Section 80EE Eligible taxpayers may claim deductions on interest paid for qualifying home loans, subject to specified conditions. 8. Section 80EEA This section provides additional deductions on eligible home loan interest for qualifying residential property purchases, where applicable. 9. Section 80EEB Tax benefits may be available on eligible loans taken for the purchase of qualifying electric vehicles, subject to statutory conditions. 10. Section 80G Donations made to eligible charitable institutions and approved funds may qualify for deductions under Section 80G, depending on the nature of the donation and eligibility requirements. 11. Section 80GG Individuals who do not receive House Rent Allowance (HRA) may be eligible to claim deductions for rent paid, subject to prescribed conditions. 12. Section 80GGA Certain eligible donations made for approved scientific research or rural development programs may qualify for deductions under this section. 13. Section 80GGC Eligible contributions made to registered political parties or approved electoral trusts may qualify for deductions, subject to applicable provisions. 14. Home Loan Interest Interest paid on eligible housing loans may qualify for deductions under relevant provisions of the Income-tax Act, subject to prescribed conditions. 15. House Rent Allowance (HRA) Eligible salaried employees receiving House Rent Allowance may claim exemptions based on applicable rules and supporting documentation. 16. Leave Travel Allowance (LTA) Eligible travel expenses within India may qualify for exemption under Leave Travel Allowance provisions, subject to prescribed conditions. 17. Standard Deduction Eligible salaried employees and pensioners may claim the standard deduction as permitted under the prevailing provisions of the Income-tax Act. 18. Interest on Savings Account Interest earned on eligible savings accounts may qualify for deductions under applicable sections, subject to statutory limits. 19. Interest on Fixed Deposits for Senior Citizens Eligible senior citizens may claim deductions on qualifying interest income as permitted under the Income-tax Act. 20. Business-Related Deductions Professionals, freelancers, and business owners may claim eligible business expenses that are wholly and exclusively incurred for business purposes, subject to proper documentation and applicable tax provisions. Examples include: Office rent Salaries and wages Professional fees Internet and communication expenses Software subscriptions Business travel Marketing expenses Depreciation on eligible assets Utility expenses Common Mistakes Taxpayers Make While Claiming Deductions Many taxpayers miss legitimate tax-saving opportunities or face issues during return processing because of avoidable mistakes. Filing an accurate Income Tax Return requires proper planning, documentation, and verification of every deduction claimed. Some common mistakes include: Claiming deductions without valid supporting documents. Selecting deductions that are not applicable under the chosen tax regime. Claiming the same deduction twice. Forgetting to verify Form 16, AIS, and Form 26AS before filing. Entering incorrect investment or insurance details. Ignoring interest income while calculating taxable income. Missing the prescribed conditions for specific deductions. Waiting until the last minute to plan tax-saving investments. Filing an incorrect ITR form. Not reconciling income reported by different sources. Carefully reviewing your financial records before filing your return helps reduce errors and improves the chances of faster return processing. Documents Required to Claim Income Tax Deductions Maintaining organized records is essential for claiming eligible deductions and responding to any future verification requirements. Common documents include: Form 16 Form 26AS Annual Information Statement (AIS) Salary slips Investment proofs Life insurance premium receipts Health insurance premium receipts Home loan interest certificate Home loan principal repayment certificate Education loan interest certificate Rent receipts (where applicable) Donation receipts Bank statements National Pension System (NPS) contribution statements Fixed Deposit certificates Business
Income Tax Return Filing 2026: Step-by-Step Guide for Salaried Employees, Freelancers & Business Owners
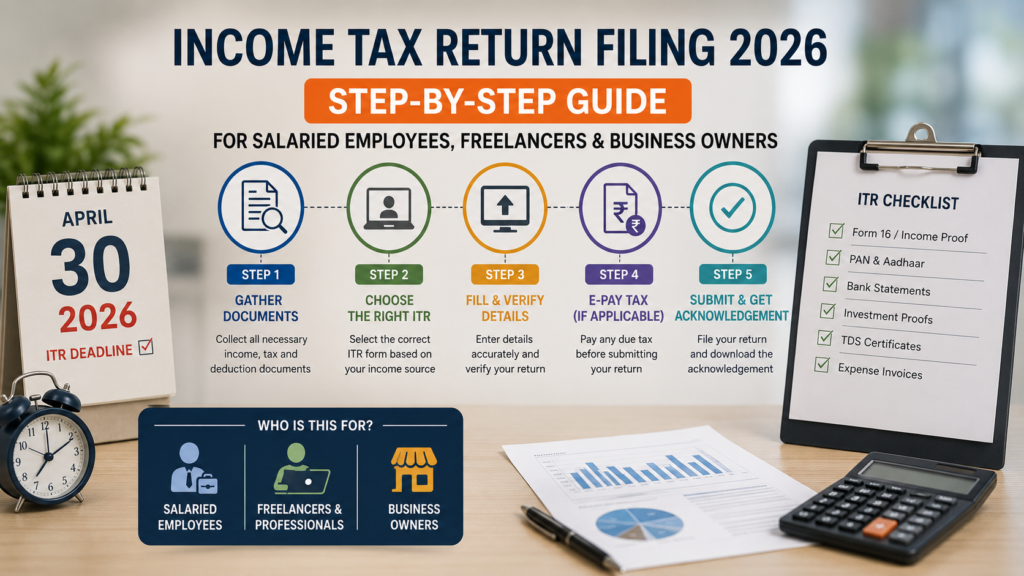
TL;DR Income Tax Return (ITR) filing is an essential annual compliance requirement for eligible taxpayers in India. Whether you’re a salaried employee, freelancer, professional, startup founder, or business owner, filing your return accurately and on time helps avoid penalties, claim refunds, maintain financial credibility, and ensure compliance with tax laws. This guide walks you through the complete ITR filing process for 2026. Understanding Income Tax Return Filing Every financial year, eligible taxpayers are required to report their income, deductions, taxes paid, and other financial details to the Income Tax Department by filing an Income Tax Return (ITR). An ITR is more than just a tax compliance document—it serves as proof of income and financial responsibility. It is often required when applying for loans, visas, government tenders, credit facilities, and various financial transactions. With increasing digital integration through the Income Tax e-Filing Portal, AIS, Form 26AS, and pre-filled returns, accurate filing has become easier—but also demands careful verification of financial information. Who Should File an Income Tax Return? Filing an Income Tax Return may be mandatory or beneficial depending on your income, business activities, and financial transactions. The following categories generally need to file ITR: Salaried Employees Individuals earning salary income above the applicable exemption limits or meeting prescribed filing conditions should file an Income Tax Return. Freelancers & Consultants Professionals providing services independently are required to report their business or professional income and comply with tax provisions applicable to them. Business Owners Proprietorships, partnership firms, LLPs, and companies must comply with applicable income tax filing requirements based on their business structure and legal obligations. Self-Employed Professionals Doctors, architects, lawyers, chartered accountants, designers, and other professionals should report their professional income through the appropriate ITR forms. Investors Individuals earning income from capital gains, dividends, interest, rental income, or foreign assets may also need to file returns depending on applicable provisions. Why Filing Your ITR Is Important Many taxpayers believe ITR filing is necessary only when tax is payable. In reality, timely filing offers several important benefits. Legal Compliance Filing your return helps you comply with the provisions of the Income-tax Act and reduces the likelihood of penalties or notices. Easier Loan Approvals Banks and financial institutions often ask for ITR acknowledgements while processing home loans, personal loans, education loans, or business finance. Faster Refund Processing If excess tax has been deducted through TDS or advance tax, filing your return is essential to claim the refund. Proof of Income ITRs serve as an accepted proof of income for visa applications, government tenders, and financial transactions. Carry Forward of Eligible Losses Timely filing may allow eligible business or capital losses to be carried forward in accordance with tax provisions. Improved Financial Credibility Regular tax compliance demonstrates financial discipline and enhances credibility with lenders, investors, and business partners. Documents Required for Income Tax Return Filing Keeping all documents ready before filing helps avoid delays and errors. Commonly required documents include: PAN Card Aadhaar Card Form 16 (for salaried employees) Form 26AS Annual Information Statement (AIS) Taxpayer Information Summary (TIS) Salary slips Bank statements Interest certificates Investment proofs Home loan certificate Capital gains statements Rental income records Business financial statements GST records (where applicable) TDS certificates Previous year’s ITR Choosing the Correct ITR Form Selecting the right ITR form is one of the most important steps in the filing process. The applicable form depends on factors such as: Nature of income Employment status Business or professional income Capital gains Foreign assets Agricultural income Presumptive taxation eligibility Using an incorrect ITR form may result in defective return notices or processing delays. Step-by-Step Income Tax Return Filing Process Step 1: Collect Financial Documents Gather all income, investment, and tax-related documents before starting the filing process. Step 2: Verify Form 26AS, AIS & TIS Cross-check the tax deducted, financial transactions, and reported income to ensure consistency with your records. Step 3: Calculate Total Income Include income from all applicable sources, such as salary, business or profession, house property, capital gains, and other sources. Step 4: Claim Eligible Deductions Review deductions available under the applicable tax regime and ensure all eligible claims are supported by proper documentation. Step 5: Select the Correct ITR Form Choose the appropriate return form based on your income profile and filing requirements. Step 6: Complete the Return Enter accurate personal details, income information, deductions, taxes paid, and bank account details. Step 7: Verify Tax Liability Check whether any additional tax is payable or whether a refund is due before submitting the return. Step 8: Submit and E-Verify the Return Complete the filing process by electronically verifying your return through the approved verification methods. Common Mistakes During ITR Filing Even small errors can delay processing or trigger notices. Avoid mistakes such as: Selecting the wrong ITR form. Ignoring AIS or Form 26AS mismatches. Omitting income from bank interest or capital gains. Claiming unsupported deductions. Providing incorrect bank account details. Failing to e-verify the return after submission. Waiting until the last date to file. Accurate preparation and careful review help ensure smooth processing. Why Hire a Chartered Accountant for Income Tax Return Filing? Although the Income Tax e-Filing Portal has made online filing more convenient, preparing an accurate Income Tax Return requires much more than simply filling out an online form. Every taxpayer’s financial situation is unique, and even small mistakes can lead to delayed refunds, notices from the Income Tax Department, or additional tax liabilities. A qualified Chartered Accountant helps ensure that your return is accurate, compliant, and optimized within the framework of applicable tax laws. A Chartered Accountant Can Help You: Select the correct ITR form. Verify Form 26AS, AIS, and TIS. Calculate taxable income accurately. Identify eligible deductions and exemptions. Report capital gains correctly. Handle business and professional income. Prepare depreciation schedules. Calculate advance tax liabilities. File revised or updated returns when necessary. Respond to Income Tax notices. Provide tax planning strategies for future financial years. Professional guidance is particularly valuable for freelancers, consultants, startups, companies, and individuals with multiple income
How to Respond to an Income Tax Notice Without Facing Penalties
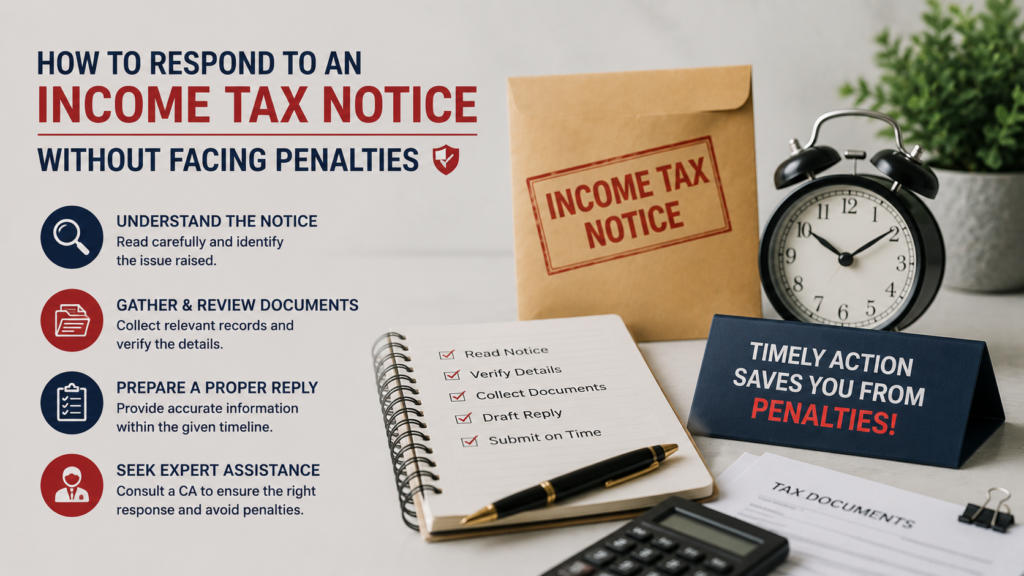
TL;DR Receiving an Income Tax Notice does not necessarily mean you’ve committed tax fraud. Many notices are issued for routine verification, mismatched information, missing documents, or clarification requests. The key is responding accurately and within the prescribed deadline. Working with an experienced Chartered Accountant can significantly reduce the risk of penalties and ensure smooth compliance. Receiving an Income Tax Notice Isn’t the End—But Ignoring It Can Be Few things create panic for taxpayers like opening an email from the Income Tax Department. Whether you’re a salaried employee, freelancer, startup founder, or business owner, receiving an Income Tax Notice can be stressful. However, it’s important to understand that most notices are not punishments—they’re requests for clarification or verification. The Income Tax Department increasingly relies on technology, AI-based data matching, and analytics to identify discrepancies between your Income Tax Return (ITR), GST filings, TDS records, Annual Information Statement (AIS), and financial transactions. If any mismatch is detected, a notice may be issued. Responding correctly—and on time—is the difference between resolving the issue smoothly and facing unnecessary penalties. Why Does the Income Tax Department Send Notices? Common reasons include: Income mismatch High-value transactions Incorrect deductions claimed Missing income disclosure TDS mismatch AIS mismatch Bank transaction discrepancies Capital gains not reported Late filing Defective ITR Tax audit selection Random scrutiny assessments Receiving a notice doesn’t automatically mean you’ve done something wrong. Common Types of Income Tax Notices Notice Type Purpose Defective Return Errors in ITR filing Scrutiny Notice Detailed examination of return Demand Notice Additional tax payable Reassessment Notice Previously undisclosed income Information Request Clarification regarding transactions Notice for Non-Filing Return not filed despite eligibility Each notice has different timelines and documentation requirements. Step 1: Stay Calm and Read the Notice Carefully Avoid reacting emotionally. Instead: Read every page. Check the section under which the notice is issued. Verify the Assessment Year. Note the response deadline. Understand exactly what information is requested. Many taxpayers respond incorrectly simply because they misunderstand the purpose of the notice. Step 2: Verify the Authenticity Before responding: Log into the Income Tax e-Filing Portal. Check whether the notice appears under your account. Match the Document Identification Number (DIN). Confirm the issuing officer’s details. Never respond to suspicious emails without verification. Step 3: Identify the Reason for the Notice The reason determines your response. Examples include: Income mismatch Perhaps your employer reported different salary figures. TDS mismatch Tax deducted may not reflect correctly. AIS mismatch Banks, mutual funds, brokers, or employers may have reported transactions differently. High-value transactions Examples: Property purchase Luxury vehicle purchase Large cash deposits Foreign travel Credit card spending The department simply seeks clarification. Step 4: Gather Supporting Documents Prepare all relevant records before submitting your response. These may include: PAN Aadhaar Income Tax Returns Form 16 Form 26AS Annual Information Statement (AIS) Bank Statements Investment Proofs Capital Gain Statements GST Returns Purchase Invoices Sale Bills Audit Reports Loan Documents Business Books of Accounts Organized documentation leads to faster resolution. Step 5: Draft a Clear and Accurate Response Your response should: Answer every query. Attach supporting documents. Be factual. Avoid assumptions. Avoid emotional explanations. Reference supporting evidence. A professional, structured reply significantly improves credibility. Step 6: Submit Before the Deadline Late responses often lead to: Penalties Interest Best judgment assessment Additional notices Prosecution in severe cases Always submit well before the due date to avoid technical issues. Step 7: Track the Status After submission: Save the acknowledgement. Monitor the Income Tax Portal. Respond quickly if additional clarification is requested. Tax proceedings may involve multiple rounds of communication. Common Mistakes That Can Lead to Penalties Many penalties arise not because of tax evasion, but because of avoidable errors such as: Ignoring the notice. Missing response deadlines. Uploading incomplete documents. Providing inaccurate information. Contradicting previously filed returns. Failing to reconcile AIS or Form 26AS data. Responding without professional review. A careful, evidence-based reply can prevent unnecessary complications and improve the chances of a quick resolution. Step 8: Seek Professional Assistance When Required While some basic notices can be handled independently, complex notices involving scrutiny, reassessment, high-value transactions, or tax demands require expert guidance. A qualified Chartered Accountant can: Interpret the legal provisions mentioned in the notice. Review your Income Tax Return for inconsistencies. Reconcile data with Form 26AS, AIS, and TIS. Prepare a legally sound response. Represent you before the Income Tax Department when required. Help minimize additional tax liabilities, interest, or penalties. Professional assistance not only saves time but also reduces the risk of making errors that could escalate the matter. Can a Chartered Accountant Respond to an Income Tax Notice on Your Behalf? Yes. A Chartered Accountant can represent taxpayers in many tax-related matters, depending on the nature of the notice and the applicable provisions under the Income-tax Act. A CA can assist with: Drafting detailed responses. Preparing supporting documentation. Reconciling tax records. Filing revised or updated returns, where applicable. Representing the taxpayer during assessments. Communicating with the Income Tax Department. For businesses and professionals with complex financial transactions, having expert representation often leads to a smoother resolution. How to Avoid Penalties After Receiving an Income Tax Notice The best way to avoid penalties is to respond proactively and accurately. Follow these best practices: ✔ Reply Before the Deadline Never wait until the last day. Early responses leave time to address any technical issues or additional requests. ✔ Submit Complete Information Incomplete responses often result in follow-up notices and prolonged assessments. ✔ Match All Financial Records Ensure consistency between: Income Tax Return (ITR) Form 26AS Annual Information Statement (AIS) Taxpayer Information Summary (TIS) GST Returns (if applicable) Bank statements Books of accounts ✔ Keep Supporting Documents Ready Maintain organized records for at least the prescribed retention period to respond quickly if questioned. ✔ Be Honest and Transparent If an error was made, acknowledge it and provide the correct information. Intentional concealment can attract more severe consequences than an honest mistake. ✔ Consult a Chartered Accountant Professional review helps identify risks before submitting your reply and ensures
Income Tax Return Filing Mistakes That Can Trigger an Income Tax Notice
TL;DR A single mistake in your Income Tax Return (ITR)—such as underreporting income, claiming incorrect deductions, or mismatching information with AIS or Form 26AS—can result in an Income Tax notice. This guide explains the most common filing errors, how to avoid them, and why working with an experienced Chartered Accountant can help individuals and businesses stay compliant and reduce tax-related risks. Introduction Income Tax Return filing has become significantly more data-driven in recent years. The Income Tax Department now cross-verifies information from multiple sources, including bank transactions, TDS records, Annual Information Statement (AIS), Taxpayer Information Summary (TIS), GST filings, mutual fund transactions, and property registrations. This advanced digital verification system means even small inconsistencies can attract scrutiny. While receiving an Income Tax notice does not automatically imply wrongdoing, responding to notices can be time-consuming, stressful, and expensive if proper documentation is unavailable. Whether you are a salaried employee, freelancer, business owner, contractor, or startup founder, understanding the most common Income Tax Return filing mistakes can help you avoid unnecessary notices and maintain complete tax compliance. Why Income Tax Notices Are Increasing The Income Tax Department now relies heavily on technology and data analytics rather than random assessments. Modern systems compare information from various financial databases to identify discrepancies. Some commonly matched data sources include: Annual Information Statement (AIS) Form 26AS Taxpayer Information Summary (TIS) GST returns PAN-linked banking transactions Property purchase and sale records Securities transactions Mutual fund investments Foreign remittances Credit card spending Because of this integrated approach, omissions that may have gone unnoticed in the past are now detected much more efficiently. How the Income Tax Department Detects Errors The Department compares information reported by taxpayers with data received from banks, employers, financial institutions, registrars, and other reporting entities. Important verification tools include: Annual Information Statement (AIS) Contains details of: Salary Interest income Dividend income Mutual fund investments Share transactions Property transactions Foreign remittances Form 26AS Shows: TDS deducted Advance tax Self-assessment tax Tax collected at source (TCS) GST Records Business turnover declared under GST is often compared with turnover declared in Income Tax Returns. PAN-Based Reporting Every significant financial transaction linked to PAN becomes part of the taxpayer’s financial profile. 15 Income Tax Return Filing Mistakes That Can Trigger an Income Tax Notice 1. Not Reporting All Sources of Income Many taxpayers report only salary income while forgetting: Savings account interest Fixed deposit interest Rental income Dividend income Freelancing income Commission Side business income Even small amounts reflected in AIS should be disclosed appropriately. 2. Mismatch Between AIS and ITR One of the most common reasons for notices is inconsistency between: AIS Form 26AS Filed ITR Before filing, carefully verify every reported transaction. 3. Selecting the Wrong ITR Form Using an incorrect ITR form may result in: Defective return notices Delayed processing Requirement to file again Always choose the return form applicable to your income category. 4. Incorrect Bank Account Details Incorrect account information may delay: Refund processing Verification Communication from the department Ensure all active bank accounts are correctly reported. 5. Claiming Deductions Without Supporting Documents Improper claims under sections such as: 80C 80D Home loan deductions Donations without valid documentation can trigger verification. Maintain: Premium receipts Investment proofs Donation certificates Loan statements 6. Ignoring Capital Gains Many taxpayers mistakenly assume that if no money is withdrawn, taxes do not apply. Capital gains may arise from: Shares Mutual funds Property sales Gold Digital assets These transactions should be reported accurately, even if tax liability is minimal. 7. Incorrect HRA Claims Claiming House Rent Allowance without: Paying rent Rent receipts PAN of landlord (where applicable) can lead to scrutiny. 8. Not Reporting Foreign Assets or Overseas Income Residents holding: Foreign bank accounts Overseas investments Foreign shares Foreign property must disclose these appropriately under applicable schedules. Failure to report can attract significant penalties. 9. Cash Deposit Mismatch Large cash deposits that do not align with declared income often invite queries. Maintain documentation explaining: Business receipts Sale proceeds Agricultural income Gifts (where applicable) 10. Claiming Excessive Business Expenses Businesses sometimes classify personal expenses as business expenses. Common examples include: Personal travel Family expenses Personal vehicle costs Non-business purchases Keep proper invoices and maintain separate personal and business accounts. 11. GST Turnover Does Not Match Income Tax Return Businesses registered under GST should ensure consistency between: GST returns Books of accounts Profit & Loss statement Income Tax Return Large variations frequently trigger scrutiny. 12. Claiming Wrong TDS Credit Never claim TDS that does not appear in: Form 26AS AIS Incorrect TDS claims often delay refunds and may result in notices. 13. Filing Return After Due Date Late filing may result in: Interest Late fees Loss of certain benefits Higher scrutiny in some cases Timely filing demonstrates better compliance. 14. Submitting Fake Investment Proofs Submitting fabricated deductions or manipulated documents is a serious compliance violation and may attract penalties and prosecution under applicable tax laws. Always maintain genuine documentation. 15. Ignoring Mistakes Instead of Filing a Revised Return If you discover an error after filing: Do not wait for a notice. File a revised return within the permitted timeline. Voluntary correction is generally preferable to departmental detection. Quick Checklist Before Filing Your ITR ✔ Verify AIS thoroughly ✔ Match Form 26AS ✔ Reconcile TDS ✔ Report every source of income ✔ Verify bank details ✔ Review capital gains ✔ Check GST turnover (for businesses) ✔ Maintain deduction proofs ✔ Use the correct ITR form ✔ Get professional review before submission Why Businesses Should Hire a Chartered Accountant Income tax laws continue to evolve, making professional guidance increasingly valuable. An experienced Chartered Accountant can help you: Select the correct ITR form Reconcile AIS and Form 26AS Identify eligible deductions Minimize tax liability legally Ensure GST and Income Tax consistency Handle notices and scrutiny professionally Maintain proper financial records Plan taxes proactively instead of reactively Professional tax advice reduces compliance risks while saving valuable time. How Junaid Khan & Co. Helps At Junaid Khan & Co., Chartered Accountants in Bhopal, we assist
Income Tax Return Filing 2026: Complete Checklist for Salaried Professionals, Freelancers & Business Owners
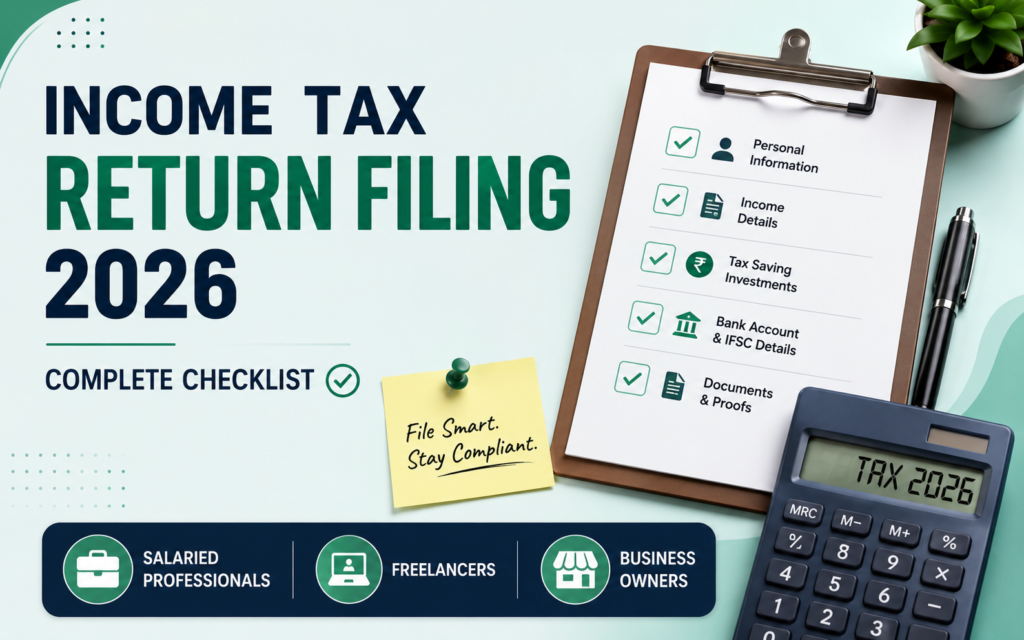
TL;DR Income Tax Return (ITR) filing is no longer just a legal formality. With increasing digital tracking, AIS reporting, PAN-based monitoring, and financial data integration, taxpayers must file accurate returns backed by proper documentation. This complete 2026 ITR filing guide explains: Documents required for tax filing ITR checklist for salaried employees Tax filing tips for freelancers Business owner compliance requirements Common filing mistakes Tax-saving preparation strategies Ways to avoid notices and penalties Why Income Tax Return Filing Matters Income tax filing plays a crucial role in: Legal tax compliance Loan and visa approvals Financial transparency Claiming refunds Carrying forward losses Maintaining clean financial records Today, the Income Tax Department uses advanced data analytics to match : Bank transactions TDS records Mutual fund investments Stock trading activity Credit card usage Property transactions Even small mismatches can trigger scrutiny or notices. For salaried individuals, freelancers, and businesses, timely and accurate filing has become essential. Who Should File an Income Tax Return? Many taxpayers incorrectly assume ITR filing is required only if taxes are payable. However, filing may be important for: Salaried employees Freelancers and consultants Proprietorship businesses Companies and LLPs Startup founders Ecommerce sellers Investors and traders Professionals earning foreign income Even individuals with lower taxable liability often file returns for: Loan eligibility Financial proof Refund claims Visa applications Compliance continuity Important Documents Required for ITR Filing Before starting your return filing, organize all financial documents properly. Document Purpose PAN Card Taxpayer identification Aadhaar Card Verification Form 16 Salary income details Form 26AS TDS verification AIS/TIS Financial transaction summary Bank Statements Income reconciliation Investment Proofs Deduction claims Home Loan Statement Interest deduction Rent Receipts HRA claims Capital Gain Statements Investment taxation Maintaining proper documentation reduces filing errors significantly. ITR Filing Checklist for Salaried Professionals Salaried employees often assume Form 16 alone is enough for filing. In reality, multiple financial disclosures must be verified. 1. Verify Form 16 Carefully Check: Salary breakup TDS deductions Employer PAN Exemptions and deductions Mismatch between Form 16 and Form 26AS can create issues. 2. Review AIS and Form 26AS AIS (Annual Information Statement) may contain: Interest income Dividend income Mutual fund transactions Securities transactions High-value banking activities Ignoring AIS discrepancies is a common reason for tax notices. 3. Declare Additional Income Many salaried individuals forget to disclose: Savings account interest FD interest Freelance side income Rental income Capital gains All taxable income must be reported. 4. Check Deduction Eligibility Review deductions under applicable provisions such as: Insurance premiums Investment-linked deductions Education loan interest Housing loan benefits Medical insurance 5. Choose Correct Tax Regime The old and new tax regimes have different deduction structures. A comparative analysis helps determine the better option. ITR Filing Checklist for Freelancers & Consultants Freelancers face unique compliance challenges because income may come from multiple clients and platforms. 1. Maintain Proper Income Records Track: Client payments Online receipts Foreign remittances Platform commissions Poor record keeping often leads to inaccurate reporting. 2. Separate Personal and Business Expenses Using separate bank accounts improves: Audit readiness Expense tracking Tax computation accuracy 3. Reconcile TDS Entries Clients may deduct TDS under different sections. Verify entries in Form 26AS. 4. Maintain Expense Documentation Freelancers should preserve: Software subscriptions Internet bills Laptop expenses Office rent Travel expenses Professional tools 5. Review Advance Tax Liability Freelancers with significant tax liability may need advance tax compliance. ITR Filing Checklist for Business Owners Business owners require deeper financial reconciliation before filing returns. 1. Finalize Bookkeeping Ensure: Sales records are accurate Expense entries are verified GST reconciliation is complete Debtors and creditors match 2. Verify GST and Income Tax Consistency Mismatch between GST turnover and income tax turnover may trigger scrutiny. 3. Review Cash Transactions Large unexplained cash transactions increase risk exposure. 4. Reconcile Bank Accounts All business bank accounts should align with accounting records. 5. Check Depreciation and Asset Records Incorrect depreciation claims are common filing errors among businesses. Choosing the Correct ITR Form Selecting the wrong ITR form can invalidate returns. Commonly Used ITR Forms ITR Form Suitable For ITR-1 Salaried individuals ITR-2 Capital gains and multiple income sources ITR-3 Business/professional income ITR-4 Presumptive taxation Form selection depends on: Income type Business structure Capital gains Foreign income Tax regime Old Tax Regime vs New Tax Regime Choosing the correct tax regime requires evaluating: Deductions available Investment structure Salary components Housing loan benefits Professional expenses Old Regime Suitable for taxpayers claiming substantial deductions. New Regime Suitable for taxpayers preferring simplified taxation with lower deductions. Tax planning should be personalized rather than generic. Common Income Tax Filing Mistakes 1. Filing Incorrect ITR Form Wrong form selection may invalidate returns. 2. Ignoring AIS Data AIS mismatches are now a major scrutiny trigger. 3. Missing Income Disclosure Undisclosed interest or side income often results in notices. 4. Incorrect Deduction Claims Unsupported deduction claims increase compliance risks. 5. Last-Minute Filing Rushed filings often lead to errors and omissions. 6. Ignoring Foreign Income Reporting Foreign assets and overseas income require proper disclosure. How to Avoid Tax Notices Maintain Accurate Documentation Organized records simplify compliance. Match All Tax Data Cross-check: Form 16 AIS 26AS Bank records Avoid Artificial Deductions Claim only genuine deductions supported by evidence. File Returns Before Deadline Timely filing improves compliance credibility. Seek Professional Review Expert review helps identify risks before submission. Why Professional Tax Assistance Matters Tax laws continue evolving every year. Professional tax assistance helps: Reduce filing errors Optimize deductions Improve compliance Handle notices Select appropriate tax regime Maintain audit-ready records This is especially important for: High-income professionals Freelancers Startups Business owners Investors How Junaid Khan & Co Supports Taxpayers Junaid Khan & Co assists individuals and businesses with: Income tax return filing Tax planning and advisory Business tax compliance Freelance taxation GST and accounting support Tax notice response assistance Financial documentation review The firm works with salaried professionals, startups, consultants, and businesses across multiple sectors. Conclusion Income Tax Return Filing in 2026 requires much more than basic data entry. Taxpayers must carefully reconcile income, deductions, financial disclosures, and compliance
Income Tax Return Filing 2026: Complete Checklist for Salaried Professionals, Freelancers & Business Owners
TL;DR Income Tax Return (ITR) filing is no longer just a legal formality. With increasing digital tracking, AIS reporting, PAN-based monitoring, and financial data integration, taxpayers must file accurate returns backed by proper documentation. This complete 2026 ITR filing guide explains: Documents required for tax filing ITR checklist for salaried employees Tax filing tips for freelancers Business owner compliance requirements Common filing mistakes Tax-saving preparation strategies Ways to avoid notices and penalties Why Income Tax Return Filing Matters Income tax filing plays a crucial role in: Legal tax compliance Loan and visa approvals Financial transparency Claiming refunds Carrying forward losses Maintaining clean financial records Today, the Income Tax Department uses advanced data analytics to match: Bank transactions TDS records Mutual fund investments Stock trading activity Credit card usage Property transactions Even small mismatches can trigger scrutiny or notices. For salaried individuals, freelancers, and businesses, timely and accurate filing has become essential. Who Should File an Income Tax Return? Many taxpayers incorrectly assume ITR filing is required only if taxes are payable. However, filing may be important for: Salaried employees Freelancers and consultants Proprietorship businesses Companies and LLPs Startup founders Ecommerce sellers Investors and traders Professionals earning foreign income Even individuals with lower taxable liability often file returns for: Loan eligibility Financial proof Refund claims Visa applications Compliance continuity Important Documents Required for ITR Filing Before starting your return filing, organize all financial documents properly. Document Purpose PAN Card Taxpayer identification Aadhaar Card Verification Form 16 Salary income details Form 26AS TDS verification AIS/TIS Financial transaction summary Bank Statements Income reconciliation Investment Proofs Deduction claims Home Loan Statement Interest deduction Rent Receipts HRA claims Capital Gain Statements Investment taxation Maintaining proper documentation reduces filing errors significantly. ITR Filing Checklist for Salaried Professionals Salaried employees often assume Form 16 alone is enough for filing. In reality, multiple financial disclosures must be verified. 1. Verify Form 16 Carefully Check: Salary breakup TDS deductions Employer PAN Exemptions and deductions Mismatch between Form 16 and Form 26AS can create issues. 2. Review AIS and Form 26AS AIS (Annual Information Statement) may contain: Interest income Dividend income Mutual fund transactions Securities transactions High-value banking activities Ignoring AIS discrepancies is a common reason for tax notices. 3. Declare Additional Income Many salaried individuals forget to disclose: Savings account interest FD interest Freelance side income Rental income Capital gains All taxable income must be reported. 4. Check Deduction Eligibility Review deductions under applicable provisions such as: Insurance premiums Investment-linked deductions Education loan interest Housing loan benefits Medical insurance 5. Choose Correct Tax Regime The old and new tax regimes have different deduction structures. A comparative analysis helps determine the better option. ITR Filing Checklist for Freelancers & Consultants Freelancers face unique compliance challenges because income may come from multiple clients and platforms. 1. Maintain Proper Income Records Track: Client payments Online receipts Foreign remittances Platform commissions Poor record keeping often leads to inaccurate reporting. 2. Separate Personal and Business Expenses Using separate bank accounts improves: Audit readiness Expense tracking Tax computation accuracy 3. Reconcile TDS Entries Clients may deduct TDS under different sections. Verify entries in Form 26AS. 4. Maintain Expense Documentation Freelancers should preserve: Software subscriptions Internet bills Laptop expenses Office rent Travel expenses Professional tools 5. Review Advance Tax Liability Freelancers with significant tax liability may need advance tax compliance. ITR Filing Checklist for Business Owners Business owners require deeper financial reconciliation before filing returns. 1. Finalize Bookkeeping Ensure: Sales records are accurate Expense entries are verified GST reconciliation is complete Debtors and creditors match 2. Verify GST and Income Tax Consistency Mismatch between GST turnover and income tax turnover may trigger scrutiny. 3. Review Cash Transactions Large unexplained cash transactions increase risk exposure. 4. Reconcile Bank Accounts All business bank accounts should align with accounting records. 5. Check Depreciation and Asset Records Incorrect depreciation claims are common filing errors among businesses. Choosing the Correct ITR Form Selecting the wrong ITR form can invalidate returns. Commonly Used ITR Forms ITR Form Suitable For ITR-1 Salaried individuals ITR-2 Capital gains and multiple income sources ITR-3 Business/professional income ITR-4 Presumptive taxation Form selection depends on: Income type Business structure Capital gains Foreign income Tax regime Old Tax Regime vs New Tax Regime Choosing the correct tax regime requires evaluating: Deductions available Investment structure Salary components Housing loan benefits Professional expenses Old Regime Suitable for taxpayers claiming substantial deductions. New Regime Suitable for taxpayers preferring simplified taxation with lower deductions. Tax planning should be personalized rather than generic. Common Income Tax Filing Mistakes 1. Filing Incorrect ITR Form Wrong form selection may invalidate returns. 2. Ignoring AIS Data AIS mismatches are now a major scrutiny trigger. 3. Missing Income Disclosure Undisclosed interest or side income often results in notices. 4. Incorrect Deduction Claims Unsupported deduction claims increase compliance risks. 5. Last-Minute Filing Rushed filings often lead to errors and omissions. 6. Ignoring Foreign Income Reporting Foreign assets and overseas income require proper disclosure. How to Avoid Tax Notices Maintain Accurate Documentation Organized records simplify compliance. Match All Tax Data Cross-check: Form 16 AIS 26AS Bank records Avoid Artificial Deductions Claim only genuine deductions supported by evidence. File Returns Before Deadline Timely filing improves compliance credibility. Seek Professional Review Expert review helps identify risks before submission. Why Professional Tax Assistance Matters Tax laws continue evolving every year. Professional tax assistance helps: Reduce filing errors Optimize deductions Improve compliance Handle notices Select appropriate tax regime Maintain audit-ready records This is especially important for: High-income professionals Freelancers Startups Business owners Investors How Junaid Khan & Co Supports Taxpayers Junaid Khan & Co assists individuals and businesses with: Income tax return filing Tax planning and advisory Business tax compliance Freelance taxation GST and accounting support Tax notice response assistance Financial documentation review The firm works with salaried professionals, startups, consultants, and businesses across multiple sectors. Conclusion Income Tax Return Filing in 2026 requires much more than basic data entry. Taxpayers must carefully reconcile income, deductions, financial disclosures, and compliance obligations. Whether you
