

TL;DR
Income tax scrutiny does not necessarily mean that a taxpayer has committed an offence. The Income Tax Department uses information available through sources such as AIS, SFT, TDS/TCS records, tax payments and other reported information to identify potential inconsistencies and compliance risks. Transactions that do not match the income declared in the ITR, unexplained investments, significant cash transactions, property purchases, foreign assets, securities transactions, large deductions and differences between GST and income-tax data can attract questions. Taxpayers should therefore review AIS, TIS, Form 26AS, bank statements, investment records and supporting documents before filing and respond carefully if a notice is received.
Introduction
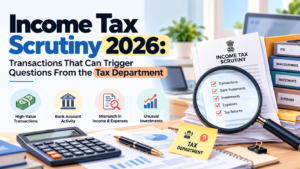
Income tax scrutiny in 2026 is increasingly data-driven.
The Income Tax Department receives financial information from taxpayers, banks, financial institutions, reporting entities and other sources. This information can appear in the taxpayer’s Annual Information Statement (AIS) and may be used for compliance verification and risk analysis.
AIS contains information such as TDS/TCS, Statement of Financial Transactions (SFT), tax payments, demand and refund information and certain other information received by the department. Taxpayers can also provide feedback where information displayed in AIS is incorrect.
This means that filing an ITR with figures that do not reasonably reconcile with information available to the department can result in questions.
Importantly, a transaction appearing in AIS does not automatically mean that it is taxable or that scrutiny will definitely happen. AIS itself states that it contains information presently available to the department and that taxpayers must independently verify all relevant information and report complete and accurate income.
The real concern is an unexplained mismatch.
What Is Income Tax Scrutiny?
Income tax scrutiny is a detailed examination of a taxpayer’s return and supporting information by the Income Tax Department.
The objective is to verify whether:
- Income has been correctly reported
- Tax has been correctly calculated
- Deductions and exemptions are genuine
- Transactions are properly explained
- Investments are supported by known sources
- Financial information is consistent
- Tax compliance requirements have been followed
A scrutiny notice does not automatically mean that additional tax is payable.
The taxpayer gets an opportunity to provide explanations and supporting documents.
For AY 2026–27 and earlier assessment years, assessment proceedings continue under the Income Tax Act, 1961 even though the Income Tax Act, 2025 has come into force from 1 April 2026. The Income Tax Department has specifically clarified that scrutiny assessments for AY 2026–27 or earlier years continue under the old Act.
Why Can a Transaction Attract Questions From the Tax Department?
The department has access to information from multiple reporting channels.
A transaction can attract attention when there is a significant difference between:
Transaction reported by a third party → Information available in AIS/SFT → Transaction disclosed in ITR
For example, if a financial institution reports a substantial transaction but the taxpayer’s return does not adequately explain the corresponding source or tax treatment, the department may seek clarification.
Similarly, a large investment funded from an income level that appears insufficient may require supporting evidence.
1. High-Value Cash Deposits
Large cash deposits into bank accounts can attract questions, particularly when they are inconsistent with the taxpayer’s declared income or normal business activity.
For example, if an individual reports modest taxable income but deposits substantial cash during the year, the department may seek information regarding:
- Source of cash
- Business receipts
- Cash sales
- Withdrawals redeposited
- Loans
- Gifts
- Agricultural income
- Other legitimate sources
Cash deposits are not automatically taxable.
However, unexplained cash transactions can create significant tax issues.
Businesses should therefore maintain proper cash books, sales records, invoices and supporting documents.
2. Large Cash Withdrawals
Large cash withdrawals can also require explanation in certain circumstances.
A withdrawal itself is not necessarily income.
However, if a taxpayer later makes a significant investment or cash deposit and claims that the funds came from earlier withdrawals, proper documentation and a credible transaction trail may be important.
The department can examine whether the explanation is consistent with the taxpayer’s financial records.
3. Property Purchases
Purchase or sale of immovable property can generate substantial financial information.
A property transaction may raise questions where:
- Purchase value is substantial compared with declared income
- Payment sources are unclear
- Loan details do not reconcile
- Co-owner contributions are unexplained
- Stamp-duty value and declared consideration require examination
- Capital gains are incorrectly reported
- Cash components are alleged or unsupported
Taxpayers should retain:
- Sale deed
- Purchase agreement
- Bank statements
- Loan documents
- Payment proofs
- Stamp-duty records
- Capital-gains computation
4. Sale of Shares and Securities
Share-market and securities transactions are increasingly visible through financial reporting systems.
Questions can arise when taxpayers fail to correctly report:
- Sale of listed shares
- Short-term capital gains
- Long-term capital gains
- Securities transactions
- Dividend income
- Mutual fund redemptions
- Other investment income
The transaction data should be reconciled with broker statements, contract notes, capital-gains statements and bank records.
5. Mutual Fund Investments and Redemptions
Large mutual fund investments or redemptions may also require reconciliation.
The taxpayer should be able to explain:
Where the investment came from → How much was invested → When it was redeemed → What gain/loss resulted → How it was reported in the ITR
A mismatch between investment records and the return can create unnecessary questions.
6. Foreign Assets and Foreign Income
Foreign financial information has become increasingly important.
The Income Tax Department announced in July 2026 that foreign-assets information received through CRS/FATCA would be made available in AIS.
Taxpayers with relevant foreign assets or income should therefore carefully review:
- Foreign bank accounts
- Foreign shares
- Foreign securities
- Foreign property
- Foreign dividends
- Foreign interest
- Foreign employment income
- Foreign pension or investment income
Where applicable, foreign assets and income should be disclosed correctly in the appropriate ITR schedules.
7. Foreign Remittances
Large outward foreign remittances or purchases of foreign currency can form part of the information available to the tax department.
AIS specifically includes certain information relating to outward foreign remittance/purchase of foreign currency.
A taxpayer should therefore maintain documentation explaining the nature and source of significant remittances.
Depending on the transaction, this may involve:
- Bank statements
- Form A2
- Purpose of remittance
- Supporting invoices
- Education or medical documents
- Investment records
- Tax documentation
8. Unexplained Investments
One of the most important scrutiny triggers is an investment that cannot be reconciled with known sources of income.
Examples include:
- Property
- Shares
- Mutual funds
- Fixed deposits
- Jewellery
- Private company investments
- Loans given
- Capital introduced into a business
The key question is usually:
What is the source of the investment?
Taxpayers should maintain a clear trail from income or financing source to the actual investment.
9. Large Jewellery Purchases
Significant jewellery purchases may attract questions where the transaction is inconsistent with the taxpayer’s disclosed financial position.
The taxpayer should retain:
- Purchase invoice
- Payment proof
- Bank statement
- Source of funds
- Gift documentation, where applicable
A jewellery purchase itself does not automatically mean that income has been concealed.
The issue arises when the taxpayer cannot satisfactorily explain the transaction.
10. High Deductions Compared With Income
Large deductions can also create inconsistencies.
Examples include claims relating to:
- Life insurance
- Health insurance
- Education-related deductions
- Donations
- Housing-loan interest
- Other eligible deductions
The deduction should be supported by appropriate documents and should satisfy the relevant legal conditions.
Taxpayers should avoid claiming deductions simply because they have historically been available.
11. Large Donations
Donation deductions can attract questions when the amount claimed is substantial or the supporting documentation is incomplete.
Before claiming a deduction, taxpayers should verify:
- Donee details
- Registration/eligibility where relevant
- Payment method
- Donation receipt
- Applicable deduction percentage
- Whether cash-payment restrictions apply
- Whether the donation qualifies under the relevant provision
A receipt alone should not be treated as sufficient if other statutory conditions are not met.
12. GST Turnover vs Income-Tax Turnover Mismatch
Businesses registered under GST should pay particular attention to the relationship between GST data and income-tax records.
A significant mismatch between:
GST turnover → Books of Accounts → Income-tax return
may require explanation.
Possible legitimate reasons include:
- Exempt supplies
- Non-GST income
- Timing differences
- Credit notes
- Advances
- Other accounting adjustments
The objective is not necessarily to make every figure identical but to ensure that differences are genuine and properly documented.
13. TDS and ITR Mismatch
TDS information is visible in AIS and other tax records.
A taxpayer may receive TDS credit from:
- Employer
- Bank
- Client
- Tenant
- Contracting party
- Other deductors
If income reported by the taxpayer does not reasonably correspond with TDS information, the department may seek clarification.
Before filing the ITR, taxpayers should reconcile:
Books/Income → TDS certificates → Form 26AS → AIS → ITR
14. Interest Income Not Reported
Interest income is frequently overlooked.
Examples include:
- Savings-account interest
- Fixed-deposit interest
- Recurring-deposit interest
- Bonds
- Debentures
- Other interest-bearing investments
Even when tax has already been deducted, the underlying income may still need to be correctly reported.
Taxpayers should reconcile bank statements and interest certificates with AIS and their ITR.
15. Dividend Income Not Properly Reported
Dividend income from shares and investments should also be reviewed.
Taxpayers should reconcile dividend information with:
- Broker statements
- Demat statements
- Bank statements
- AIS
- TDS information
This becomes especially important when investments are spread across multiple brokers or financial institutions.
16. Loans and Gifts Without Supporting Documents
Large loans received or gifts claimed as sources of funds can attract questions if documentation is weak.
For loans, taxpayers should generally maintain evidence such as:
- Loan agreement
- Bank transfer records
- Lender details
- Repayment records
- Interest records where applicable
For gifts, the nature of the relationship, documentation and applicable tax provisions should be reviewed.
17. Unexplained Business Expenses
Businesses may also attract questions when expenses are unusually high or poorly supported.
Common areas include:
- Cash expenses
- Related-party expenses
- Personal expenses booked as business expenses
- Large professional fees
- Commission payments
- Unusual purchases
- Expenses without proper invoices
Businesses should maintain proper books and supporting documents for significant expenses.
18. Related-Party Transactions
Transactions with relatives, directors, partners or connected entities can require additional scrutiny.
Examples include:
- Loans to related parties
- Loans received from related parties
- Property transactions
- Salary or remuneration
- Interest payments
- Business purchases
- Expenses paid on behalf of related persons
The transaction should have a genuine business or financial basis and should be properly recorded.
19. Sudden Increase in Income or Expenses
Significant changes from previous years may require explanation.
For example:
- Income doubles suddenly
- Business turnover falls sharply
- Expenses increase substantially
- Large deductions appear for the first time
- Capital gains suddenly become significant
- Professional receipts change dramatically
A change is not inherently suspicious.
However, taxpayers should maintain records that explain genuine changes in their financial position.
20. Inconsistency Between Bank Statements and ITR
Bank statements provide a useful financial trail.
A mismatch can arise when:
- Interest income is omitted
- Business receipts are not properly recorded
- Investments are not explained
- Large transfers are incorrectly classified
- Loans are incorrectly treated as income
- Personal and business transactions are mixed
Maintaining separate business and personal accounts can make reconciliation easier.
AIS: The Most Important Pre-Filing Check
One of the most useful steps taxpayers can take before filing an ITR is to review their AIS.
The Income Tax Department describes AIS as a comprehensive view of information available about a taxpayer. It contains TDS/TCS, SFT, tax payments and other information, and allows taxpayers to provide feedback on reported information.
However, taxpayers should not assume that AIS contains every transaction.
The department specifically states that there may be other transactions relating to a taxpayer that are not presently displayed in AIS. Taxpayers are expected to check all relevant information and report complete and accurate income.
Therefore:
AIS review ≠ complete tax compliance
It is one part of the overall reconciliation process.
What Should You Check Before Filing Your ITR?
A practical pre-filing review can include:
Income Reconciliation
Compare:
- Salary
- Business income
- Professional receipts
- Interest
- Dividends
- Rental income
- Capital gains
- Foreign income
- Other taxable income
Tax Information Reconciliation
Compare:
- AIS
- TIS
- Form 26AS
- TDS certificates
- TCS certificates
- Advance tax
- Self-assessment tax
Financial Transaction Reconciliation
Review:
- Bank statements
- Investments
- Property transactions
- Securities transactions
- Loans
- Gifts
- Major purchases
- Foreign remittances
What Should You Do If AIS Contains Incorrect Information?
An AIS entry is not necessarily final.
The Income Tax Department allows taxpayers to provide feedback on information displayed in AIS. AIS can show both reported and modified values after feedback or source confirmation.
If information is incorrect, the taxpayer should:
- Identify the incorrect transaction.
- Check the underlying documents.
- Determine whether the reporting entity made an error.
- Submit appropriate feedback through AIS where applicable.
- Maintain supporting evidence.
- Report the correct tax position in the ITR.
A taxpayer should not simply ignore an incorrect AIS entry.
Does Every High-Value Transaction Trigger Scrutiny?
No.
A high-value transaction does not automatically mean that a scrutiny notice will be issued.
The department uses information and risk-management mechanisms to identify cases requiring further examination.
Under the new Income Tax Act, 2025, information identified under the Board’s risk-management strategy is expressly included among information that can suggest income has escaped assessment for reassessment purposes.
Therefore, taxpayers should focus less on avoiding legitimate transactions and more on maintaining:
Genuine transaction + documented source + correct reporting + consistent records
How to Reduce the Risk of Unnecessary Tax Questions
Taxpayers and businesses can follow a simple compliance process.
Step 1: Review AIS
Check TDS, SFT, tax payments and other information.
Step 2: Reconcile Bank Statements
Identify major receipts, investments, transfers and expenses.
Step 3: Reconcile Investments
Match mutual funds, shares, property and other investments with funding sources.
Step 4: Check TDS
Compare TDS certificates with Form 26AS, AIS and the ITR.
Step 5: Review Deductions
Keep documentary evidence for deductions and exemptions.
Step 6: Check Foreign Transactions
Review foreign assets, income and remittances wherever applicable.
Step 7: Reconcile GST for Businesses
Compare GST returns with books and income-tax figures.
Step 8: Maintain Supporting Documents
Keep invoices, agreements, bank statements, certificates and other evidence supporting material transactions.
What If You Receive an Income Tax Scrutiny Notice?
Receiving a scrutiny notice does not mean that the taxpayer has automatically been found guilty of tax evasion.
The taxpayer should first read the notice carefully and identify:
- Assessment year/tax year
- Notice section
- Information requested
- Response deadline
- Documents required
- Specific transactions questioned
The response should address the actual questions raised rather than providing unrelated documents.
Taxpayers should also preserve proof of submission and monitor the proceeding through the income-tax e-filing portal.
Important 2026 Transition Point
The Income Tax Act, 2025 applies to the new tax-year framework from 1 April 2026.
However, older assessment proceedings do not automatically shift to the new Act.
For example, scrutiny assessment for AY 2026–27 and earlier years continues under the Income Tax Act, 1961.
This distinction is important when responding to a notice because taxpayers should first identify the relevant assessment year or tax year and then determine which Act and provisions apply.
Income Tax Scrutiny Checklist for 2026
Before filing or responding to a notice, taxpayers should review:
- AIS
- TIS
- Form 26AS
- TDS certificates
- Bank statements
- Salary records
- Business income
- Professional receipts
- Interest income
- Dividend income
- Capital gains
- Property transactions
- Share transactions
- Mutual fund transactions
- Large cash deposits
- Large cash withdrawals
- Loans received
- Loans given
- Gifts
- Jewellery purchases
- Foreign assets
- Foreign income
- Foreign remittances
- Major deductions
- Donations
- GST turnover, where applicable
- Advance tax
- Self-assessment tax
- Outstanding tax demands
- Supporting documents
Conclusion
Income tax scrutiny in 2026 is increasingly connected to the financial information available with the tax department.
AIS can contain TDS/TCS information, SFT transactions, tax payments and other information received from reporting sources. The department also uses risk-management information for compliance and assessment processes.
Transactions such as large cash deposits, property purchases, securities transactions, foreign assets, foreign remittances, unexplained investments, major deductions, GST mismatches and differences between AIS and the ITR can therefore require closer attention.
However, a high-value transaction does not automatically mean tax scrutiny.
The best protection is accurate reporting and a clear documentary trail. Taxpayers should reconcile AIS, TDS, bank statements, investments and income before filing the return and should respond carefully and within the prescribed timeline if a notice is received.
For 2026, taxpayers should also distinguish between proceedings governed by the Income Tax Act, 1961 and those governed by the Income Tax Act, 2025, particularly during the transition between AY 2026–27 and Tax Year 2026–27.
Frequently Asked Questions
1. What transactions can trigger income tax scrutiny in 2026?
Large cash deposits, unexplained investments, property transactions, securities transactions, foreign assets, foreign remittances, major deductions, GST mismatches and discrepancies between AIS and the ITR can attract questions depending on the circumstances.
2. Does a high-value transaction automatically trigger an income tax notice?
No. A high-value transaction does not automatically result in scrutiny. The department considers available information, risk factors and the overall tax profile of the taxpayer.
3. Can AIS mismatch result in an income tax notice?
An unexplained mismatch between AIS information and the income reported in the ITR can result in compliance questions. However, AIS itself is not necessarily a final determination of taxable income.
4. What is AIS in income tax?
Annual Information Statement (AIS) is a comprehensive information statement available to taxpayers through the income-tax e-filing portal. It can contain TDS/TCS, SFT, tax payments and other information available with the department.
5. Should I report an AIS transaction if it is incorrect?
Taxpayers should verify the underlying transaction. Where the information is incorrect, appropriate feedback can be provided through AIS and supporting documentation should be maintained.
6. Can cash deposits attract income tax scrutiny?
Large or unusual cash deposits can result in questions about their source, particularly where they are inconsistent with the taxpayer’s disclosed financial position. Genuine business receipts and other legitimate sources should be supported with appropriate records.
7. Can property purchases attract an income tax notice?
A substantial property transaction may require clarification regarding the source of funds, payment trail, ownership and tax treatment. Proper purchase documents and payment records should therefore be maintained.
8. Are foreign assets important for income tax compliance in 2026?
Yes. Foreign assets and foreign income can have specific disclosure and reporting requirements. The Income Tax Department also announced the availability of foreign-assets information received through CRS/FATCA in AIS in 2026.
9. Does GST turnover need to match income-tax turnover?
Not necessarily. Differences can arise because of exempt supplies, non-GST items, timing differences, credit notes and other accounting adjustments. Material differences should be properly reconciled and documented.
10. What should I do after receiving an income tax scrutiny notice?
Read the notice carefully, identify the assessment year and specific information requested, collect supporting documents and submit a clear response within the prescribed deadline. For complex cases, professional tax advice can help ensure that the response addresses the issues raised accurately.
Blog By : CA Junaid Khan
Written by CA Junaid Ahmed Khan, Junaid Khan & Co., Bhopal.
