

September–October 2026 Business Compliance Checklist for SMEs & Companies
TL;DR September and October 2026 are important compliance months for Indian SMEs and companies. Businesses need to manage GST returns, TDS payments, advance tax, tax-audit requirements, accounting reconciliations and quarterly TDS statements while also preparing for upcoming income-tax and corporate compliance. For September, businesses should particularly track the 15 September advance-tax instalment, monthly GST filings, TDS payments and the 30 September tax-audit deadline applicable to eligible taxpayers for FY 2025–26. October then brings the Q2 TDS statement deadline of 31 October, along with regular GST and TDS compliance. A structured compliance checklist can help SMEs and companies avoid late fees, interest, penalties and last-minute reporting errors. Introduction September and October are among the busiest compliance months for Indian businesses. For SMEs, startups, partnership firms and companies, compliance during this period is not limited to GST return filing. Businesses may also need to manage advance tax, TDS/TCS, tax audit, income-tax reporting, accounting reconciliations and other statutory requirements. The challenge becomes greater when multiple compliance deadlines fall close together. A missed GST filing, incorrect TDS deposit or incomplete tax-audit information can create unnecessary interest, late fees, notices or reconciliation issues. Businesses should therefore maintain a monthly compliance calendar and complete important reconciliations before the actual filing deadlines. Here is a practical September–October 2026 business compliance checklist for SMEs and companies. September 2026 Business Compliance Checklist 1. Review and Pay the Second Advance Tax Instalment One of the most important September tax deadlines is the second instalment of advance tax. For taxpayers following the regular instalment schedule, the cumulative advance-tax requirement reaches 45% of the estimated annual advance-tax liability by 15 September. Before making the payment, businesses should estimate their current-year taxable income and consider: Revenue earned so far Expected profit for the year TDS/TCS credits Capital gains Other taxable income Major business expenses Changes in profitability Tax already paid Businesses should avoid simply repeating the previous instalment without reviewing their latest financial position. 2. File GSTR-1 for August 2026 Monthly GST taxpayers generally need to file GSTR-1 for the previous month’s outward supplies by the applicable due date. GSTR-1 contains important sales and invoice information that subsequently affects GST reporting and recipient-side input tax credit. Before filing, businesses should verify: B2B invoices B2C sales Credit notes Debit notes Export invoices Amendments GSTINs Taxable values Tax rates HSN/SAC information GSTR-1 is required even where there is no business activity for the relevant tax period, subject to the applicable filing framework. 3. Review GSTR-2B and Input Tax Credit Before filing the relevant GSTR-3B, businesses should reconcile purchase records with GSTR-2B. The review should identify: Missing purchase invoices Incorrect GSTINs Duplicate invoices Credit notes Supplier filing delays Ineligible ITC Reverse-charge transactions Differences between books and GSTR-2B Businesses should remember that an invoice appearing in GSTR-2B does not by itself establish that every condition for claiming ITC has been satisfied. 4. File GSTR-3B and Pay GST Liability For monthly filers, GSTR-3B is generally due on the 20th of the following month. The return is used to declare GST liabilities and discharge the applicable tax. Before filing, businesses should reconcile: GSTR-1 GSTR-2B Books of accounts Sales register Purchase register Credit/debit notes Reverse charge liability GST payments GSTN also states that GSTR-3B cannot be amended after filing, making pre-filing verification especially important. 5. Deposit TDS for August 2026 Businesses deducting TDS should generally deposit tax deducted during August by 7 September 2026, subject to the applicable exceptions. The accounting records should be reconciled with: TDS payable ledger Challans Vendor payments Salary records Professional fees Rent Commission Contractor payments The Income Tax Department confirms that the general TDS deposit timeline continues to be the 7th of the following month under the current framework. 6. Complete the Tax Audit for FY 2025–26 For businesses covered by tax-audit requirements, September is particularly important. For FY 2025–26 / AY 2026–27, tax audits continue under the Income Tax Act, 1961. Depending on the circumstances, Form 3CA-3CD or Form 3CB-3CD is applicable. Businesses should ensure that the auditor has received: Final trial balance Profit and loss account Balance sheet Bank statements Fixed-asset register GST records TDS records Loan details Debtor and creditor details Expense ledgers MSME information Related-party transaction details Supporting documents The tax-audit report deadline for standard cases is 30 September 2026. 7. Reconcile Books With GST September is a good time to perform a detailed GST-to-books reconciliation. Businesses should compare: Sales Register → GSTR-1 → GSTR-3B → Books of Accounts Differences may arise because of: Timing differences Credit notes Sales returns Advances Amendments Exempt supplies Export transactions Accounting adjustments Unexplained differences should be investigated before they become a larger compliance problem. October 2026 Business Compliance Checklist 8. File the Q2 TDS Statement The July–September 2026 quarter ends on 30 September. Businesses deducting TDS should prepare their quarterly TDS statement for Q2. Under the Income Tax Act, 2025 framework, Form 140 is the quarterly TDS statement for resident non-salary payments, while Form 138 applies to quarterly salary TDS reporting. The Q2 due date is 31 October. Businesses should reconcile the statement before filing to minimise: PAN errors Incorrect TDS amounts Wrong section reporting Challan mismatches Duplicate entries Incorrect deductee information 9. Reconcile TDS With Books and AIS After completing the quarter, businesses should compare TDS records with their accounting system. Check: TDS deducted TDS deposited Vendor-wise deductions Salary TDS TDS receivable TDS payable Form 26AS/AIS information TDS return data The objective is to ensure that the amount recorded in the books agrees with the tax actually deducted and deposited. 10. Review October GST Compliance October continues the regular GST cycle. Businesses should prepare their sales and purchase data early instead of waiting until the filing deadline. The monthly GST process should include: Finalise sales data Reconcile invoices Review GSTR-1 data Check GSTR-2B Reconcile ITC Calculate GST liability Review reverse charge File GSTR-1 File GSTR-3B Preserve filing records For monthly taxpayers, GSTR-1 is generally due on the 11th and GSTR-3B on the 20th of the following month, subject to applicable rules and extensions.
September 2026 Tax Compliance Calendar: All Important Income Tax, GST & TDS Deadlines
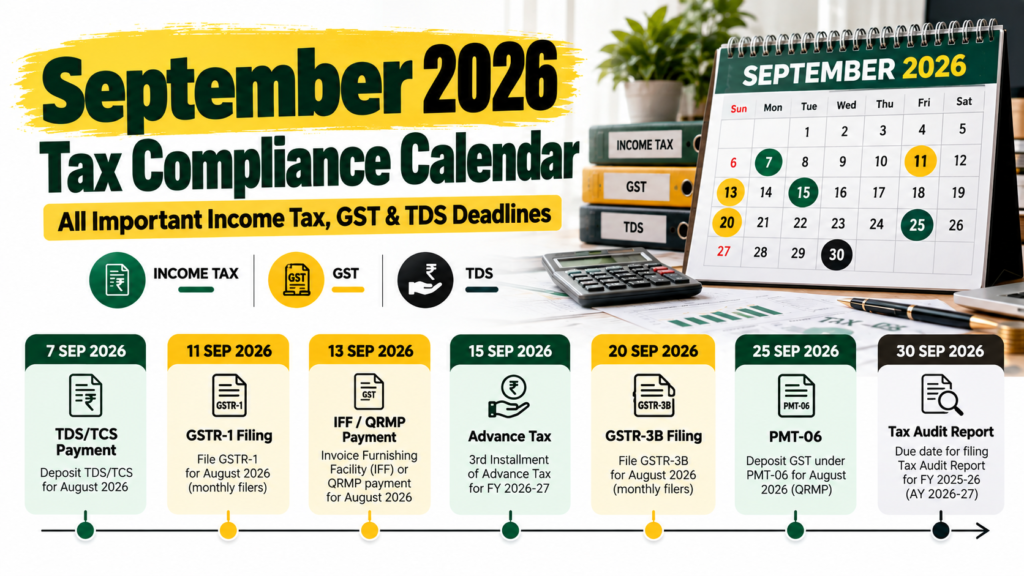
TL;DR September 2026 is an important compliance month for Indian businesses because it includes the second advance-tax instalment deadline on 15 September, regular GST return deadlines, TDS payment obligations and the 30 September tax-audit deadline for AY 2026–27. TDS for August is generally payable by 7 September, while monthly GST taxpayers generally have GSTR-1 and GSTR-3B deadlines on 11 and 20 September respectively. Businesses should reconcile their books, GST records, TDS data and advance-tax calculations before the respective deadlines. Introduction September is one of the most important months in the Indian tax-compliance calendar. Businesses, professionals, employers and taxpayers have multiple statutory obligations to track during the month. From TDS payment and GST return filing to advance tax and tax audit, missing even one deadline can result in interest, late fees, penalties or other compliance issues. September 2026 is particularly important because taxpayers earning business or professional income need to make the second instalment of advance tax by 15 September, while taxpayers covered by tax-audit requirements for FY 2025–26 / AY 2026–27 need to furnish their tax-audit report by 30 September in the standard cases. This September 2026 tax compliance calendar provides a practical overview of the major Income Tax, GST and TDS deadlines that businesses and taxpayers should track. September 2026 Tax Compliance Calendar at a Glance Date Compliance Who Should Check It 7 September 2026 TDS payment for August 2026 Tax deductors 11 September 2026 GSTR-1 for August 2026 Monthly GST filers 13 September 2026 IFF for August 2026 Eligible QRMP taxpayers opting for IFF 15 September 2026 Second advance-tax instalment Taxpayers liable to pay advance tax 20 September 2026 GSTR-3B for August 2026 Monthly GST filers 30 September 2026 Tax-audit report for AY 2026–27 Taxpayers subject to tax audit These are the key recurring deadlines relevant to September. Applicability can vary based on taxpayer category, filing frequency, transaction type and any specific statutory extension. 7 September 2026: TDS Payment for August Tax deductors generally need to deposit TDS deducted during August 2026 by 7 September 2026. The Income Tax Department confirms that the general TDS payment rule continues to require deposit by the 7th of the following month, with specified exceptions for certain challan-cum-statement transactions and March deductions. The corresponding rules under the Income Tax Act, 2025 retain the same basic timeline. Businesses should verify: TDS deducted during August Applicable TDS rates PAN details of deductees TDS ledger balances Challan amounts Date of deduction Date of payment or credit Applicable new Income Tax Act provisions Why TDS reconciliation matters Simply depositing TDS is not enough. Businesses should also ensure that the amount deducted in their books agrees with the amount deposited and subsequently reported. Incorrect TDS can create problems during quarterly statement filing and may result in interest or other consequences. 11 September 2026: GSTR-1 for August Monthly GST taxpayers generally need to furnish GSTR-1 for August 2026 by 11 September 2026. GSTR-1 reports outward supplies and therefore plays an important role in the GST compliance chain. Before filing, businesses should verify: B2B invoices B2C supplies Export transactions Credit notes Debit notes Amendments GSTIN of customers Invoice numbers Taxable value GST rates E-invoice data, where applicable Errors in GSTR-1 can subsequently affect recipients’ Input Tax Credit and create reconciliation issues. 13 September 2026: IFF for QRMP Taxpayers Eligible taxpayers under the QRMP scheme who choose to use the Invoice Furnishing Facility (IFF) should also track the applicable September deadline. For the August 2026 period, the relevant IFF filing deadline falls on 13 September 2026. IFF allows eligible QRMP taxpayers to furnish specified invoice details for the first two months of a quarter. Businesses using IFF should reconcile invoices before uploading them rather than relying on corrections later. 15 September 2026: Second Advance Tax Instalment One of the most important September deadlines is the second advance-tax instalment. For taxpayers liable to pay advance tax, the September instalment is generally due on 15 September. Under the new Income Tax Act, 2025 framework, the prescribed instalment schedule continues to require cumulative payment of 45% of the estimated annual advance-tax liability by 15 September, after reducing amounts already paid in earlier instalments. Who should pay advance tax? Advance tax can apply to individuals, businesses, professionals, companies and other taxpayers whose estimated tax liability meets the applicable conditions. For businesses, advance-tax calculations should consider expected: Business income Professional income Capital gains Interest income Rental income Other taxable income TDS/TCS credits Previous advance-tax payments Why September advance tax is important Businesses often underestimate their tax liability because they calculate advance tax only using previous-year figures. Instead, taxpayers should review their current-year income and expected tax liability before making the September payment. A significant shortfall can potentially result in interest consequences under the applicable provisions. Under the Income Tax Act, 2025, Section 424 corresponds to the earlier Section 234B and Section 425 corresponds to Section 234C. How Businesses Should Calculate September Advance Tax A practical approach is: Step 1: Estimate Current-Year Income Prepare an updated estimate of taxable income for Tax Year 2026–27. Step 2: Calculate Estimated Tax Calculate tax based on the applicable provisions and tax regime. Step 3: Reduce Available Credits Consider eligible: TDS TCS Advance tax already paid Other applicable tax credits Step 4: Compare With Previous Instalments Calculate the remaining advance-tax liability after considering payments already made. Step 5: Pay the Required Instalment Ensure payment is completed by the applicable deadline. Businesses should revisit their estimates if profits change substantially during the year rather than blindly following the original estimate. 20 September 2026: GSTR-3B for August Monthly GST taxpayers generally need to file GSTR-3B for August 2026 by 20 September 2026. GSTR-3B summarises GST liability and eligible Input Tax Credit and is used to discharge the taxpayer’s GST liability. Before filing, businesses should reconcile: Sales register Purchase register GSTR-1 GSTR-2B IMS records, where applicable Credit and debit notes Reverse-charge transactions GST payments Previous-period adjustments GSTR-2B vs GSTR-3B reconciliation Businesses should not assume that every amount appearing in GSTR-2B is automatically
September 2026 Tax Compliance Calendar: ITR, TDS, GST & Audit Due Dates
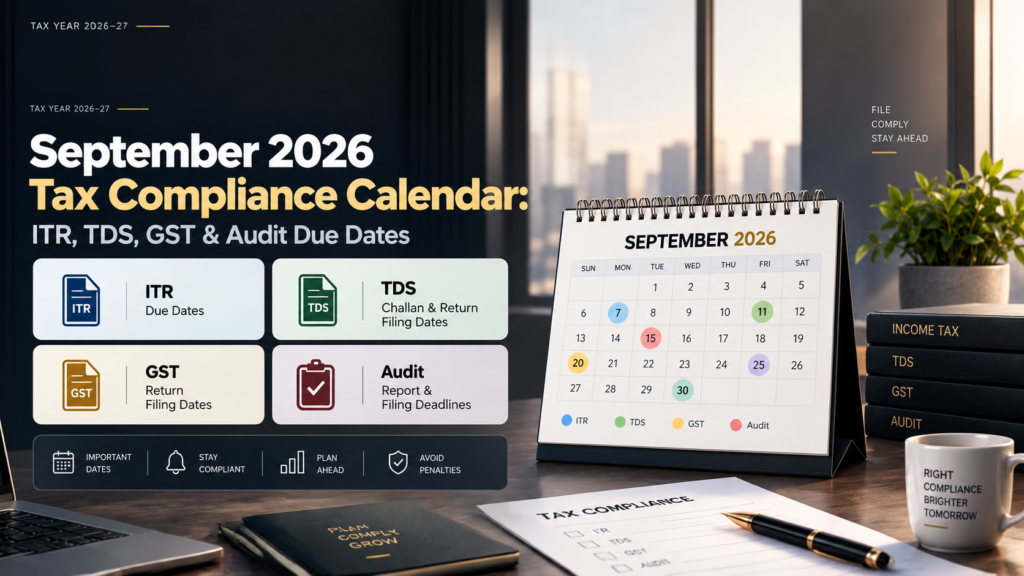
TL;DR September 2026 is an important compliance month for Indian taxpayers and businesses. Key deadlines include the 15 September 2026 advance-tax instalment, monthly TDS payment by 7 September, GSTR-1 by 11 September and GSTR-3B by 20 September for monthly filers. The month also includes the 30 September 2026 tax-audit report deadline for applicable FY 2025–26 cases. For businesses and professionals, September is particularly important because tax audit documentation, GST reconciliations, TDS records and advance-tax calculations often overlap. Since Tax Year 2026–27 is governed by the Income Tax Act, 2025, taxpayers should also understand the transition between the old and new income-tax provisions. However, the tax audit report for FY 2025–26 / AY 2026–27 continues to be governed by the Income Tax Act, 1961 and uses the existing Forms 3CA/3CB/3CD. Introduction September is one of the most important months in the Indian tax compliance calendar. While many taxpayers associate September mainly with Advance Tax, businesses have several other obligations to track during the month. These can include GST returns, TDS payments, TDS statements, tax-audit preparation and, for eligible taxpayers, the filing of audit reports. Missing one deadline may result in late fees, interest, loss of certain tax benefits or unnecessary compliance notices. This makes a September 2026 Tax Compliance Calendar particularly useful for business owners, professionals, freelancers, companies and finance teams. The important dates should not be considered in isolation. A taxpayer may have multiple obligations falling within the same month, and each one may require different documents and calculations. September 2026 Tax Compliance Calendar at a Glance The major September deadlines can be broadly grouped as follows: 7 September 2026 – TDS Payment TDS deducted during August 2026 is generally required to be deposited with the Government by 7 September 2026, subject to applicable exceptions. 11 September 2026 – GSTR-1 Monthly GST taxpayers generally need to file GSTR-1 for August 2026 by 11 September 2026. 15 September 2026 – Second Advance Tax Instalment Eligible taxpayers generally need to achieve 45% cumulative payment of estimated annual advance tax by 15 September 2026. 20 September 2026 – GSTR-3B Monthly GST filers generally need to file GSTR-3B for August 2026 by 20 September 2026 and discharge the corresponding GST liability. 30 September 2026 – Tax Audit Report For applicable FY 2025–26 / AY 2026–27 tax-audit cases, the tax-audit report is due by 30 September 2026. The exact compliance obligation can vary depending on the taxpayer’s category, filing frequency, audit status and applicable notifications. 7 September 2026: TDS Payment Due Date One of the first important September compliance dates is the TDS payment deadline. Generally, tax deducted at source during August 2026 must be deposited with the Central Government by 7 September 2026. The Income Tax Department confirms that the general rule continues to require TDS to be deposited by the 7th of the following month. The Income Tax Rules, 2026 retain the same general timeline. For example, if a business deducts TDS on eligible payments made during August, the applicable TDS amount generally needs to be deposited by 7 September. Why TDS Payment Should Be Checked Carefully Businesses should reconcile: TDS deducted during August TDS payable TDS actually deposited Challan details Deductee information PAN details Applicable TDS provisions A mismatch between books, challans and TDS statements can create unnecessary compliance problems later. Are There Exceptions to the 7 September TDS Deadline? Yes. Certain types of TDS have separate timelines. The Income Tax Department specifically notes that certain challan-cum-statement provisions, including specified transactions involving property, rent, payments by certain individuals/HUFs and virtual digital assets under the old provisions, have a different 30-day timeline from the end of the month of deduction. Therefore, businesses should not assume that every TDS payment follows exactly the same deadline. 11 September 2026: GSTR-1 Due Date For regular taxpayers filing GST returns monthly, GSTR-1 for August 2026 is generally due on 11 September 2026. GSTR-1 contains details of outward supplies and is an important source of information for the recipient’s GST records and input-tax-credit reconciliation. The GST Portal states that the normal due date for monthly GSTR-1 is the 11th day of the succeeding month, unless the Government extends the deadline through notification. What Should Businesses Check Before Filing GSTR-1? Before filing, businesses should reconcile their sales data with: Sales register Tax invoices Debit notes Credit notes E-invoices, where applicable E-way bill information GST books Customer GSTINs Correct reporting is important because errors in outward-supply data can affect the recipient’s ITC reconciliation. What Happens If GSTR-1 Is Filed Late? Late filing can result in applicable late fees and can create downstream compliance problems. The GST Portal also indicates that failure to file GSTR-1 can trigger a system-generated return-defaulter notice in the prescribed circumstances. Therefore, businesses should avoid treating GSTR-1 as merely an administrative formality. 15 September 2026: Advance Tax 45% Rule For many taxpayers, 15 September 2026 is the most important tax deadline of the month. The second advance-tax instalment for Tax Year 2026–27 is due on this date. By 15 September, eligible taxpayers generally need to have paid 45% of their estimated annual advance-tax liability cumulatively. The Income Tax Department’s guidance states the following advance-tax schedule: 15 June – 15% 15 September – 45% 15 December – 75% 15 March – 100% How Does the 45% Rule Work? The 45% requirement is cumulative. Suppose your estimated annual advance-tax liability is ₹2,00,000. By 15 September: ₹2,00,000 × 45% = ₹90,000 If you already paid ₹30,000 in June, you would generally need another: ₹90,000 − ₹30,000 = ₹60,000 Therefore, your cumulative advance-tax payment becomes ₹90,000. Who Needs to Pay Advance Tax? Advance tax can apply where the taxpayer’s estimated tax liability reaches the prescribed threshold after considering relevant tax credits. It can affect: Business owners Professionals Freelancers Consultants Investors Landlords Salaried taxpayers with substantial additional income Income such as interest, rental income, bonds and capital gains can increase tax liability even when salary TDS is already being deducted. Advance Tax Under the Income Tax Act, 2025 Tax Year 2026–27
