

October 2026 Income Tax Compliance: What Businesses Should Prepare After Tax Audit
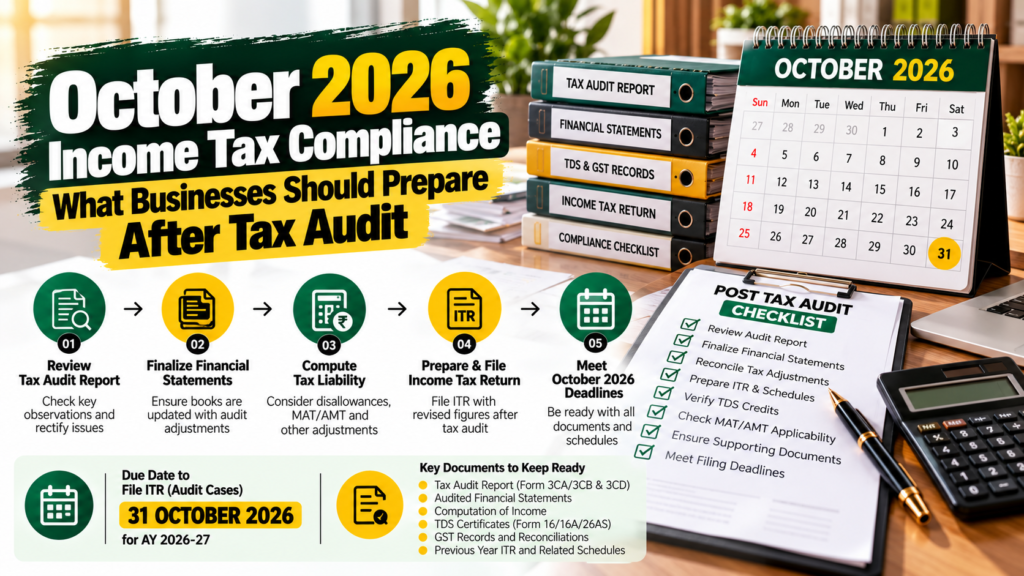
TL;DR October 2026 is an important compliance month for businesses that have completed their tax audit for FY 2025–26. After the tax-audit report is filed, businesses should review the audit figures, reconcile Form 3CD with the books and ITR, finalize the income-tax computation, pay any remaining tax liability and file the applicable ITR by the prescribed deadline. For AY 2026–27, businesses subject to tax audit generally have an ITR due date of 31 October 2026, while the tax-audit report is generally due by 30 September 2026. Businesses should also review TDS/TCS records, advance tax, GST reconciliations, carried-forward losses, depreciation, disallowances and outstanding tax demands before finalizing their October compliance. Introduction Completing a tax audit does not mean that a business’s income-tax compliance for FY 2025–26 is finished. The tax audit is an important stage in the compliance process, but businesses still need to ensure that the information reported in the audit report is correctly reflected in the income-tax return. This makes October 2026 particularly important for businesses that are required to file their audited ITR for AY 2026–27. For FY 2025–26, the applicable return continues to be governed by the Income Tax Act, 1961 because the income relates to the financial year beginning before 1 April 2026. The Income Tax Department has clarified that AY 2026–27 remains under the old Act even though the return is filed after the new Income Tax Act, 2025 has come into force. Once the tax audit report has been completed, businesses should use October to complete the remaining income-tax compliance carefully rather than simply uploading the ITR based on the audit figures. What Happens After the Tax Audit? A typical post-tax-audit process involves: Reviewing the final tax-audit report. Reconciling Form 3CD with the books. Finalizing taxable income. Checking tax already paid. Calculating the final tax liability or refund. Reviewing TDS and TCS credits. Checking advance-tax payments. Preparing and filing the applicable ITR. Verifying the return. Preserving supporting records. The tax audit report and ITR should tell a consistent financial and tax story. Differences between the two should be investigated before filing. 1. Review the Final Tax Audit Report The first step after the audit is to carefully review the final tax-audit report. For FY 2025–26, taxpayers subject to tax audit continue to use Form 3CA or Form 3CB along with Form 3CD, depending on the applicable circumstances. The tax-audit report is generally due by 30 September 2026 for cases where the corresponding ITR due date is 31 October 2026. Businesses should check: Name and PAN Assessment year Nature of business Turnover Gross receipts Depreciation Disallowances Statutory dues TDS/TCS information Loans and deposits MSME-related information Related-party transactions GST-related information Other Form 3CD disclosures Any obvious error should be discussed with the tax auditor before the return is finalized. 2. Reconcile Form 3CD With the ITR One of the most important October compliance checks is ensuring that the information in Form 3CD agrees with the corresponding information reported in the ITR. The Income Tax Department’s AY 2026–27 validation framework contains checks relating to audit information and requires relevant ITR details to be consistent with the applicable audit particulars. Businesses should compare: Turnover Gross receipts Profit Depreciation Taxable income Disallowances Brought-forward losses Depreciation carried forward Tax audit details TDS/TCS Tax payments A mismatch does not always mean that the return is incorrect, but unexplained differences should not be ignored. 3. Finalize the Taxable Income The audited profit shown in the financial statements is not necessarily the same as taxable income. Businesses may need to make tax adjustments for: Depreciation Disallowable expenses Statutory dues Employee-related payments TDS-related disallowances Certain cash transactions Expenses subject to specific tax provisions Brought-forward losses Tax deductions Other income-tax adjustments The final taxable income should be calculated after considering the relevant provisions of the Income Tax Act, 1961 applicable to FY 2025–26. 4. Check the ITR Filing Due Date For audited businesses, the ITR due date for AY 2026–27 is generally 31 October 2026 in cases where the taxpayer is not subject to transfer-pricing provisions. The tax-audit report generally precedes the return by one month. Transfer-pricing cases can have a different timeline, with the applicable return due date generally extending to 30 November 2026. Therefore, businesses should not assume that every audited taxpayer has the same October deadline. 5. Reconcile TDS and TCS Credits Before filing the ITR, businesses should verify whether all eligible TDS and TCS credits have been correctly reflected. The reconciliation should cover: Form 26AS AIS TDS certificates TDS ledger TCS records Customer/vendor records Tax deducted by customers Tax collected from applicable transactions If tax credit in the books does not match the tax credit available in the income-tax records, the difference should be investigated before filing. Incorrect TDS or TCS claims can affect the final tax payable or refund. 6. Verify Advance Tax Payments Businesses should reconcile all advance-tax instalments paid during FY 2025–26. The reconciliation should include: Challan date BSR code Challan serial number Amount paid Assessment year Tax head Total advance tax paid The advance-tax figures should match the tax records available on the income-tax portal. If there is an outstanding tax liability after considering advance tax, TDS and TCS, the business should calculate and pay the applicable amount before filing the return. 7. Calculate Any Remaining Self-Assessment Tax After finalizing taxable income and adjusting available tax credits, the business should determine whether any additional tax remains payable. This can arise because: Actual profit was higher than estimated. Additional income was identified during audit. Certain expenses were disallowed. TDS was lower than expected. Advance tax was insufficient. Tax deductions were reduced. Other taxable income was identified. Any remaining liability should be properly calculated before submitting the ITR. 8. Check Interest and Other Tax Consequences Businesses should not calculate only the basic income-tax liability. Where applicable, they should also review interest arising from: Short payment of advance tax Deferment of advance tax Delay in filing the return Other applicable statutory defaults For AY 2026–27, the relevant provisions continue
