

September 2026 Tax Compliance Calendar: All Important Income Tax, GST & TDS Deadlines
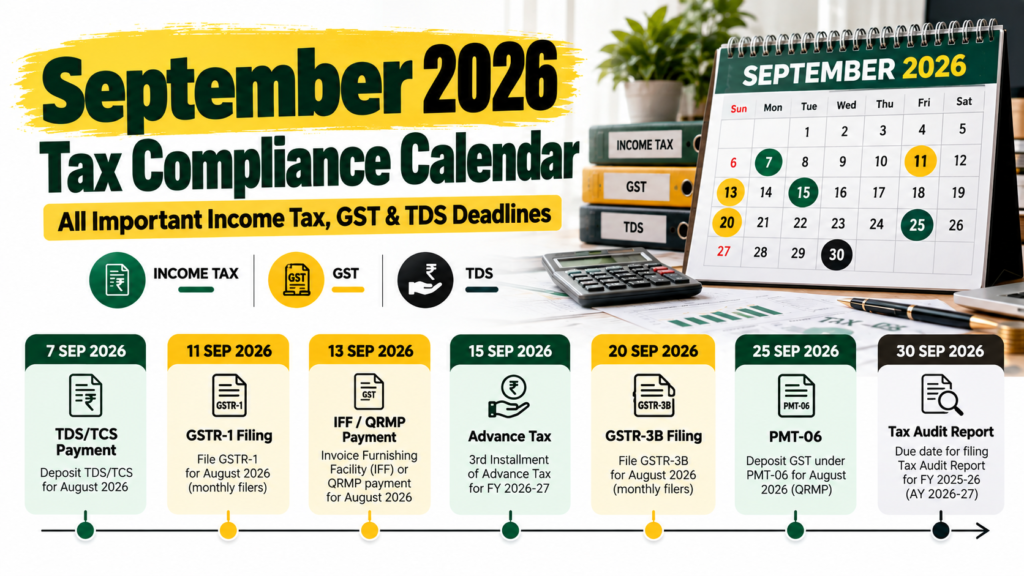
TL;DR September 2026 is an important compliance month for Indian businesses because it includes the second advance-tax instalment deadline on 15 September, regular GST return deadlines, TDS payment obligations and the 30 September tax-audit deadline for AY 2026–27. TDS for August is generally payable by 7 September, while monthly GST taxpayers generally have GSTR-1 and GSTR-3B deadlines on 11 and 20 September respectively. Businesses should reconcile their books, GST records, TDS data and advance-tax calculations before the respective deadlines. Introduction September is one of the most important months in the Indian tax-compliance calendar. Businesses, professionals, employers and taxpayers have multiple statutory obligations to track during the month. From TDS payment and GST return filing to advance tax and tax audit, missing even one deadline can result in interest, late fees, penalties or other compliance issues. September 2026 is particularly important because taxpayers earning business or professional income need to make the second instalment of advance tax by 15 September, while taxpayers covered by tax-audit requirements for FY 2025–26 / AY 2026–27 need to furnish their tax-audit report by 30 September in the standard cases. This September 2026 tax compliance calendar provides a practical overview of the major Income Tax, GST and TDS deadlines that businesses and taxpayers should track. September 2026 Tax Compliance Calendar at a Glance Date Compliance Who Should Check It 7 September 2026 TDS payment for August 2026 Tax deductors 11 September 2026 GSTR-1 for August 2026 Monthly GST filers 13 September 2026 IFF for August 2026 Eligible QRMP taxpayers opting for IFF 15 September 2026 Second advance-tax instalment Taxpayers liable to pay advance tax 20 September 2026 GSTR-3B for August 2026 Monthly GST filers 30 September 2026 Tax-audit report for AY 2026–27 Taxpayers subject to tax audit These are the key recurring deadlines relevant to September. Applicability can vary based on taxpayer category, filing frequency, transaction type and any specific statutory extension. 7 September 2026: TDS Payment for August Tax deductors generally need to deposit TDS deducted during August 2026 by 7 September 2026. The Income Tax Department confirms that the general TDS payment rule continues to require deposit by the 7th of the following month, with specified exceptions for certain challan-cum-statement transactions and March deductions. The corresponding rules under the Income Tax Act, 2025 retain the same basic timeline. Businesses should verify: TDS deducted during August Applicable TDS rates PAN details of deductees TDS ledger balances Challan amounts Date of deduction Date of payment or credit Applicable new Income Tax Act provisions Why TDS reconciliation matters Simply depositing TDS is not enough. Businesses should also ensure that the amount deducted in their books agrees with the amount deposited and subsequently reported. Incorrect TDS can create problems during quarterly statement filing and may result in interest or other consequences. 11 September 2026: GSTR-1 for August Monthly GST taxpayers generally need to furnish GSTR-1 for August 2026 by 11 September 2026. GSTR-1 reports outward supplies and therefore plays an important role in the GST compliance chain. Before filing, businesses should verify: B2B invoices B2C supplies Export transactions Credit notes Debit notes Amendments GSTIN of customers Invoice numbers Taxable value GST rates E-invoice data, where applicable Errors in GSTR-1 can subsequently affect recipients’ Input Tax Credit and create reconciliation issues. 13 September 2026: IFF for QRMP Taxpayers Eligible taxpayers under the QRMP scheme who choose to use the Invoice Furnishing Facility (IFF) should also track the applicable September deadline. For the August 2026 period, the relevant IFF filing deadline falls on 13 September 2026. IFF allows eligible QRMP taxpayers to furnish specified invoice details for the first two months of a quarter. Businesses using IFF should reconcile invoices before uploading them rather than relying on corrections later. 15 September 2026: Second Advance Tax Instalment One of the most important September deadlines is the second advance-tax instalment. For taxpayers liable to pay advance tax, the September instalment is generally due on 15 September. Under the new Income Tax Act, 2025 framework, the prescribed instalment schedule continues to require cumulative payment of 45% of the estimated annual advance-tax liability by 15 September, after reducing amounts already paid in earlier instalments. Who should pay advance tax? Advance tax can apply to individuals, businesses, professionals, companies and other taxpayers whose estimated tax liability meets the applicable conditions. For businesses, advance-tax calculations should consider expected: Business income Professional income Capital gains Interest income Rental income Other taxable income TDS/TCS credits Previous advance-tax payments Why September advance tax is important Businesses often underestimate their tax liability because they calculate advance tax only using previous-year figures. Instead, taxpayers should review their current-year income and expected tax liability before making the September payment. A significant shortfall can potentially result in interest consequences under the applicable provisions. Under the Income Tax Act, 2025, Section 424 corresponds to the earlier Section 234B and Section 425 corresponds to Section 234C. How Businesses Should Calculate September Advance Tax A practical approach is: Step 1: Estimate Current-Year Income Prepare an updated estimate of taxable income for Tax Year 2026–27. Step 2: Calculate Estimated Tax Calculate tax based on the applicable provisions and tax regime. Step 3: Reduce Available Credits Consider eligible: TDS TCS Advance tax already paid Other applicable tax credits Step 4: Compare With Previous Instalments Calculate the remaining advance-tax liability after considering payments already made. Step 5: Pay the Required Instalment Ensure payment is completed by the applicable deadline. Businesses should revisit their estimates if profits change substantially during the year rather than blindly following the original estimate. 20 September 2026: GSTR-3B for August Monthly GST taxpayers generally need to file GSTR-3B for August 2026 by 20 September 2026. GSTR-3B summarises GST liability and eligible Input Tax Credit and is used to discharge the taxpayer’s GST liability. Before filing, businesses should reconcile: Sales register Purchase register GSTR-1 GSTR-2B IMS records, where applicable Credit and debit notes Reverse-charge transactions GST payments Previous-period adjustments GSTR-2B vs GSTR-3B reconciliation Businesses should not assume that every amount appearing in GSTR-2B is automatically
Tax Audit 2026: Complete Checklist of Documents, Deadlines & Common Mistakes
TL;DR Tax audit is an important compliance requirement for eligible businesses and professionals. For FY 2025–26 (AY 2026–27), tax audit continues under Section 44AB of the Income-tax Act, 1961, with the tax audit report generally due by 30 September 2026. The applicable forms are Form 3CA/3CB along with Form 3CD. From Tax Year 2026–27, the corresponding provision under the Income Tax Act, 2025 is Section 63, and the new unified Form 26 will be used. Introduction Tax audit is more than simply checking a business’s financial statements. It involves examining books of account, financial transactions, tax deductions, payments, statutory compliance and other information that must be reported to the Income Tax Department. For businesses and professionals covered by tax-audit provisions, incomplete records or incorrect reporting can create unnecessary compliance problems. This is especially important in 2026 because India is going through a transition from the Income-tax Act, 1961 to the Income Tax Act, 2025. For FY 2025–26, taxpayers continue to follow the old Act for tax-audit reporting. The new Act applies to income earned from 1 April 2026, which is referred to as Tax Year 2026–27. Understanding the applicable threshold, documents, forms, deadlines and common errors can make the tax-audit process much smoother. What Is a Tax Audit? A tax audit is an examination of the accounts of certain taxpayers by a Chartered Accountant to verify and report specified financial and tax information under the applicable provisions of the Income Tax law. For FY 2025–26, the requirement is governed by Section 44AB of the Income-tax Act, 1961. The audit report provides information about the taxpayer’s accounts and specified particulars that help the Income Tax Department assess compliance. Tax audit is therefore not simply about checking whether the business made a profit or loss. It involves reviewing financial and tax-related information in detail. Who Is Required to Get a Tax Audit in 2026? The applicability depends on the nature of income, turnover or gross receipts and other prescribed conditions. Tax Audit for Business Generally, tax audit applies where business turnover or gross receipts exceed ₹1 crore. However, the threshold can increase to ₹10 crore where both cash receipts and cash payments do not exceed 5% of the relevant total receipts and payments, subject to the applicable conditions. Tax Audit for Professionals For specified professions, the threshold is generally ₹50 lakh of gross receipts. Professionals should also consider whether other conditions relating to presumptive taxation or declaring income below prescribed levels trigger audit requirements. Presumptive Taxation Cases Certain taxpayers opting out of presumptive taxation and declaring income below the prescribed threshold can also become subject to tax-audit requirements. Because applicability depends on the specific facts of the taxpayer, businesses should evaluate the applicable provisions before assuming that they are outside the audit requirement. Tax Audit Deadline for FY 2025–26 For FY 2025–26 / AY 2026–27, the tax audit report is due by 30 September 2026 in cases where the corresponding ITR due date is 31 October 2026. For transfer-pricing cases, a different timeline may apply. Therefore, businesses should confirm the applicable due date based on their specific circumstances. The important point is that taxpayers should not wait until the last few days to begin preparing their audit documents. Which Forms Are Used for Tax Audit in 2026? For FY 2025–26, the old Income-tax Act, 1961 framework continues to apply. Form 3CA and Form 3CD Form 3CA is applicable where the taxpayer’s accounts have already been audited under another law. Form 3CD contains the statement of particulars required to be reported under Section 44AB. Form 3CB and Form 3CD Form 3CB is generally used in cases where the taxpayer is required to obtain a tax audit report but the accounts are not audited under another law. It is accompanied by Form 3CD. What Changes Under the Income Tax Act, 2025? One of the major changes businesses need to understand is the transition to the new Income Tax Act, 2025. For Tax Year 2026–27, Section 63 corresponds to the old Section 44AB tax-audit provision. The Income Tax Department has confirmed that the tax-audit thresholds remain the same. The reporting form also changes. Instead of separate Forms 3CA, 3CB and 3CD, the new framework uses Form 26, which consolidates the earlier audit forms into a unified tax-audit report. For Tax Year 2026–27, the tax-audit report due date is 30 September 2027. Complete Tax Audit 2026 Document Checklist Preparing documents early can significantly reduce last-minute errors. 1. Books of Account Keep updated: Cash book Bank book General ledger Purchase register Sales register Journal entries Expense records Debtors ledger Creditors ledger Fixed asset register The books should be properly reconciled before the audit begins. 2. Bank Statements Provide complete bank statements for all business accounts. The auditor may need to verify: Business receipts Payments Loans Interest Bank charges Transfers Large or unusual transactions Closing balances Bank balances should be reconciled with the books. 3. Sales and Purchase Records Maintain detailed sales and purchase documentation, including invoices and supporting records. For GST-registered businesses, it is also important to reconcile accounting records with GST returns. 4. GST Records Depending on the business, relevant GST documents can include: GST registration details GSTR-1 GSTR-3B GSTR-2B GSTR-9, where applicable E-invoices E-way bills Input Tax Credit workings GST payment challans Credit and debit notes Differences between books and GST records should be investigated before finalisation. 5. TDS and TCS Records Keep: TDS returns TDS challans TDS certificates TCS records, where applicable Vendor TDS details Salary TDS records Form 26AS/AIS reconciliation The Income Tax Department’s AIS includes information such as TDS/TCS, SFT information, tax payments, demand/refund and other reported information. 6. Fixed Asset and Depreciation Details Maintain a fixed asset register containing: Asset description Purchase date Purchase value Additions Disposals Depreciation Closing written-down value Supporting invoices should also be retained. 7. Loan and Interest Documents If the business has loans, maintain: Loan statements Sanction letters Interest certificates Repayment schedules Security documentation Details of loans received or repaid This helps verify both principal and
