

September 2026 Tax Compliance Calendar: ITR, TDS, GST & Audit Due Dates
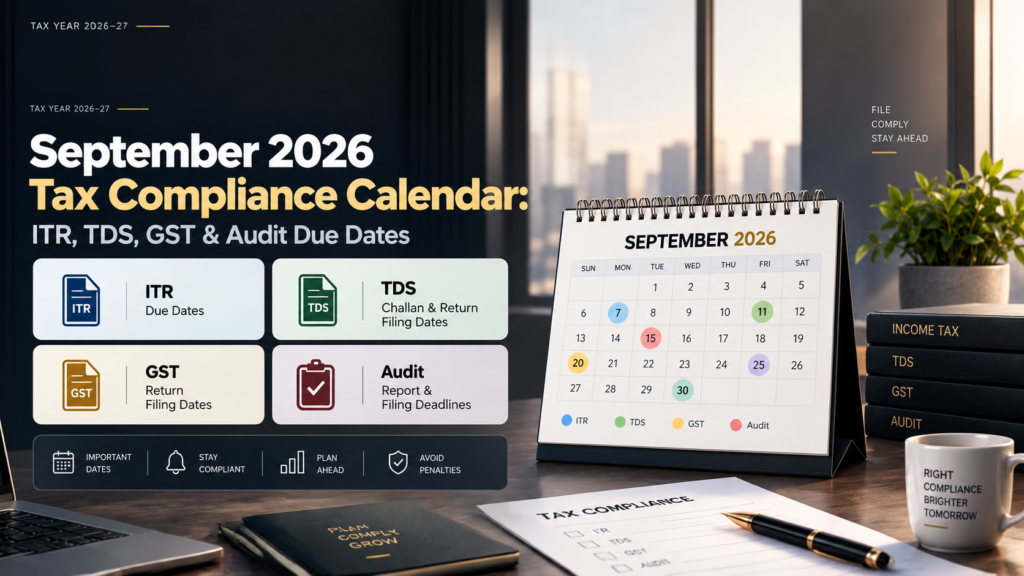
TL;DR September 2026 is an important compliance month for Indian taxpayers and businesses. Key deadlines include the 15 September 2026 advance-tax instalment, monthly TDS payment by 7 September, GSTR-1 by 11 September and GSTR-3B by 20 September for monthly filers. The month also includes the 30 September 2026 tax-audit report deadline for applicable FY 2025–26 cases. For businesses and professionals, September is particularly important because tax audit documentation, GST reconciliations, TDS records and advance-tax calculations often overlap. Since Tax Year 2026–27 is governed by the Income Tax Act, 2025, taxpayers should also understand the transition between the old and new income-tax provisions. However, the tax audit report for FY 2025–26 / AY 2026–27 continues to be governed by the Income Tax Act, 1961 and uses the existing Forms 3CA/3CB/3CD. Introduction September is one of the most important months in the Indian tax compliance calendar. While many taxpayers associate September mainly with Advance Tax, businesses have several other obligations to track during the month. These can include GST returns, TDS payments, TDS statements, tax-audit preparation and, for eligible taxpayers, the filing of audit reports. Missing one deadline may result in late fees, interest, loss of certain tax benefits or unnecessary compliance notices. This makes a September 2026 Tax Compliance Calendar particularly useful for business owners, professionals, freelancers, companies and finance teams. The important dates should not be considered in isolation. A taxpayer may have multiple obligations falling within the same month, and each one may require different documents and calculations. September 2026 Tax Compliance Calendar at a Glance The major September deadlines can be broadly grouped as follows: 7 September 2026 – TDS Payment TDS deducted during August 2026 is generally required to be deposited with the Government by 7 September 2026, subject to applicable exceptions. 11 September 2026 – GSTR-1 Monthly GST taxpayers generally need to file GSTR-1 for August 2026 by 11 September 2026. 15 September 2026 – Second Advance Tax Instalment Eligible taxpayers generally need to achieve 45% cumulative payment of estimated annual advance tax by 15 September 2026. 20 September 2026 – GSTR-3B Monthly GST filers generally need to file GSTR-3B for August 2026 by 20 September 2026 and discharge the corresponding GST liability. 30 September 2026 – Tax Audit Report For applicable FY 2025–26 / AY 2026–27 tax-audit cases, the tax-audit report is due by 30 September 2026. The exact compliance obligation can vary depending on the taxpayer’s category, filing frequency, audit status and applicable notifications. 7 September 2026: TDS Payment Due Date One of the first important September compliance dates is the TDS payment deadline. Generally, tax deducted at source during August 2026 must be deposited with the Central Government by 7 September 2026. The Income Tax Department confirms that the general rule continues to require TDS to be deposited by the 7th of the following month. The Income Tax Rules, 2026 retain the same general timeline. For example, if a business deducts TDS on eligible payments made during August, the applicable TDS amount generally needs to be deposited by 7 September. Why TDS Payment Should Be Checked Carefully Businesses should reconcile: TDS deducted during August TDS payable TDS actually deposited Challan details Deductee information PAN details Applicable TDS provisions A mismatch between books, challans and TDS statements can create unnecessary compliance problems later. Are There Exceptions to the 7 September TDS Deadline? Yes. Certain types of TDS have separate timelines. The Income Tax Department specifically notes that certain challan-cum-statement provisions, including specified transactions involving property, rent, payments by certain individuals/HUFs and virtual digital assets under the old provisions, have a different 30-day timeline from the end of the month of deduction. Therefore, businesses should not assume that every TDS payment follows exactly the same deadline. 11 September 2026: GSTR-1 Due Date For regular taxpayers filing GST returns monthly, GSTR-1 for August 2026 is generally due on 11 September 2026. GSTR-1 contains details of outward supplies and is an important source of information for the recipient’s GST records and input-tax-credit reconciliation. The GST Portal states that the normal due date for monthly GSTR-1 is the 11th day of the succeeding month, unless the Government extends the deadline through notification. What Should Businesses Check Before Filing GSTR-1? Before filing, businesses should reconcile their sales data with: Sales register Tax invoices Debit notes Credit notes E-invoices, where applicable E-way bill information GST books Customer GSTINs Correct reporting is important because errors in outward-supply data can affect the recipient’s ITC reconciliation. What Happens If GSTR-1 Is Filed Late? Late filing can result in applicable late fees and can create downstream compliance problems. The GST Portal also indicates that failure to file GSTR-1 can trigger a system-generated return-defaulter notice in the prescribed circumstances. Therefore, businesses should avoid treating GSTR-1 as merely an administrative formality. 15 September 2026: Advance Tax 45% Rule For many taxpayers, 15 September 2026 is the most important tax deadline of the month. The second advance-tax instalment for Tax Year 2026–27 is due on this date. By 15 September, eligible taxpayers generally need to have paid 45% of their estimated annual advance-tax liability cumulatively. The Income Tax Department’s guidance states the following advance-tax schedule: 15 June – 15% 15 September – 45% 15 December – 75% 15 March – 100% How Does the 45% Rule Work? The 45% requirement is cumulative. Suppose your estimated annual advance-tax liability is ₹2,00,000. By 15 September: ₹2,00,000 × 45% = ₹90,000 If you already paid ₹30,000 in June, you would generally need another: ₹90,000 − ₹30,000 = ₹60,000 Therefore, your cumulative advance-tax payment becomes ₹90,000. Who Needs to Pay Advance Tax? Advance tax can apply where the taxpayer’s estimated tax liability reaches the prescribed threshold after considering relevant tax credits. It can affect: Business owners Professionals Freelancers Consultants Investors Landlords Salaried taxpayers with substantial additional income Income such as interest, rental income, bonds and capital gains can increase tax liability even when salary TDS is already being deducted. Advance Tax Under the Income Tax Act, 2025 Tax Year 2026–27
